If you are in your thirties, retirement probably feels like a problem for a much older version of you. The EMI is real, the rent is real, the child’s school admission is real — retirement is an abstract date three decades away. That is exactly why your thirties are the best time to start. Retirement planning in your 30s is not about giving up your present life for a distant future. It is about putting a modest amount to work early enough that time does most of the heavy lifting, instead of forcing your fifties to do it under pressure.
The honest answer to “how much should I save” is: it depends on your income, your expenses, and the life you want after 60. But there is a practical range most salaried people can aim for. If you can save and invest 20 to 30 percent of your take-home pay for retirement and other long-term goals combined, you are in strong shape. On a take-home salary of Rs 70,000 a month, that is Rs 14,000 to Rs 21,000. If that sounds like a lot right now, start with whatever you can — even Rs 5,000 a month — and raise it every year as your salary grows. The starting amount matters less than the habit and the years ahead of you.
Why Starting at 30 Beats Starting at 40
There is no magic to compounding. It is just growth on top of growth, year after year, and the only ingredient you cannot buy later is time. A simple comparison makes this concrete. Suppose two friends both invest Rs 10,000 a month in a diversified equity mutual fund through a SIP, earning an average return of 12 percent a year. Priya starts at 30 and invests until 60. Rahul starts at 40 and invests until 60.
Priya invests for 30 years, putting in Rs 36 lakh of her own money, and ends up with roughly Rs 3.5 crore. Rahul invests for 20 years, putting in Rs 24 lakh, and ends up with roughly Rs 99 lakh. Priya put in only Rs 12 lakh more than Rahul, but she ends up with about Rs 2.5 crore more. That gap is not cleverness. It is ten extra years of growth, and it is the single biggest advantage your thirties give you. Wait until 40, and you would need to invest nearly three times as much each month to reach the same final number.
Returns will not actually be a smooth 12 percent every year. Some years markets fall, some years they surge, and a real SIP journey will feel bumpy. The comparison still holds in spirit: the earlier you start, the less you have to save each month, and the more room you have to recover from bad years. Starting late is not hopeless — plenty of people build solid retirements starting at 40 — but it is measurably harder, and it usually means a tighter lifestyle in the saving years.
How to Estimate Your Retirement Number in Today’s Rupees
People avoid this calculation because it sounds technical. It is actually three simple steps. First, work out what you spend in a month today, excluding costs that will disappear by retirement — like your home loan EMI if the loan ends before 60, or children’s education fees. Suppose that figure is Rs 50,000 a month, or Rs 6 lakh a year. Second, decide how much of that lifestyle you want to maintain after retirement. Many planners use 70 to 80 percent of pre-retirement expenses, since commuting, work clothes, and some other costs drop away. Third, remember that Rs 50,000 a month today will not be Rs 50,000 a month in 30 years, because prices rise. That is inflation, and it is the part most people underestimate.
At 6 percent annual inflation, something that costs Rs 50,000 today will cost about Rs 2.87 lakh a month in 30 years. That number shocks people, and it should — but it does not mean you need to panic. Your income will also rise over those 30 years, and so will your investments if they grow faster than inflation. The point of the exercise is to size your goal in future rupees so your monthly SIP is aimed at the right target, not at a number that made sense in 2026 prices.
Once you have a rough annual expense figure for your retirement years, multiply it by 25 as a starting-point rule of thumb. This is the popular “25 times annual expenses” idea: if you expect to spend Rs 10 lakh a year in retirement (in the prices of that time), a corpus of about Rs 2.5 crore gives you a reasonable base, assuming it keeps growing modestly while you withdraw from it. This is a guideline, not a guarantee, and it assumes you also have other income like EPF or a pension. Treat the result as a direction, not a verdict, and revisit it every few years as your life changes.
Inflation: The Quiet Force Working Against You
Inflation deserves its own moment because it quietly decides whether your savings are enough. A fixed deposit earning 7 percent when inflation is 6 percent is growing your money by barely 1 percent in real terms. Over 30 years, that difference compounds into a huge gap. This is why retirement money cannot sit entirely in fixed deposits, no matter how safe they feel. Safety from market ups and downs is not the same as safety from rising prices.
Equity mutual funds, for all their volatility, have historically beaten inflation over long periods in India, which is why they form the core of most retirement plans for people in their thirties. You do not need to pick exotic funds. A broad index fund or a flexi-cap fund, held for decades, is the workhorse for most salaried investors. As you get closer to 60, you gradually shift money towards safer options — debt funds, fixed deposits, Senior Citizens’ Savings Scheme — so a market fall just before retirement does not damage the money you are about to live on. That gradual shift, from growth to safety, is the whole strategy in one line.
The Roles of EPF, NPS, and Mutual Funds
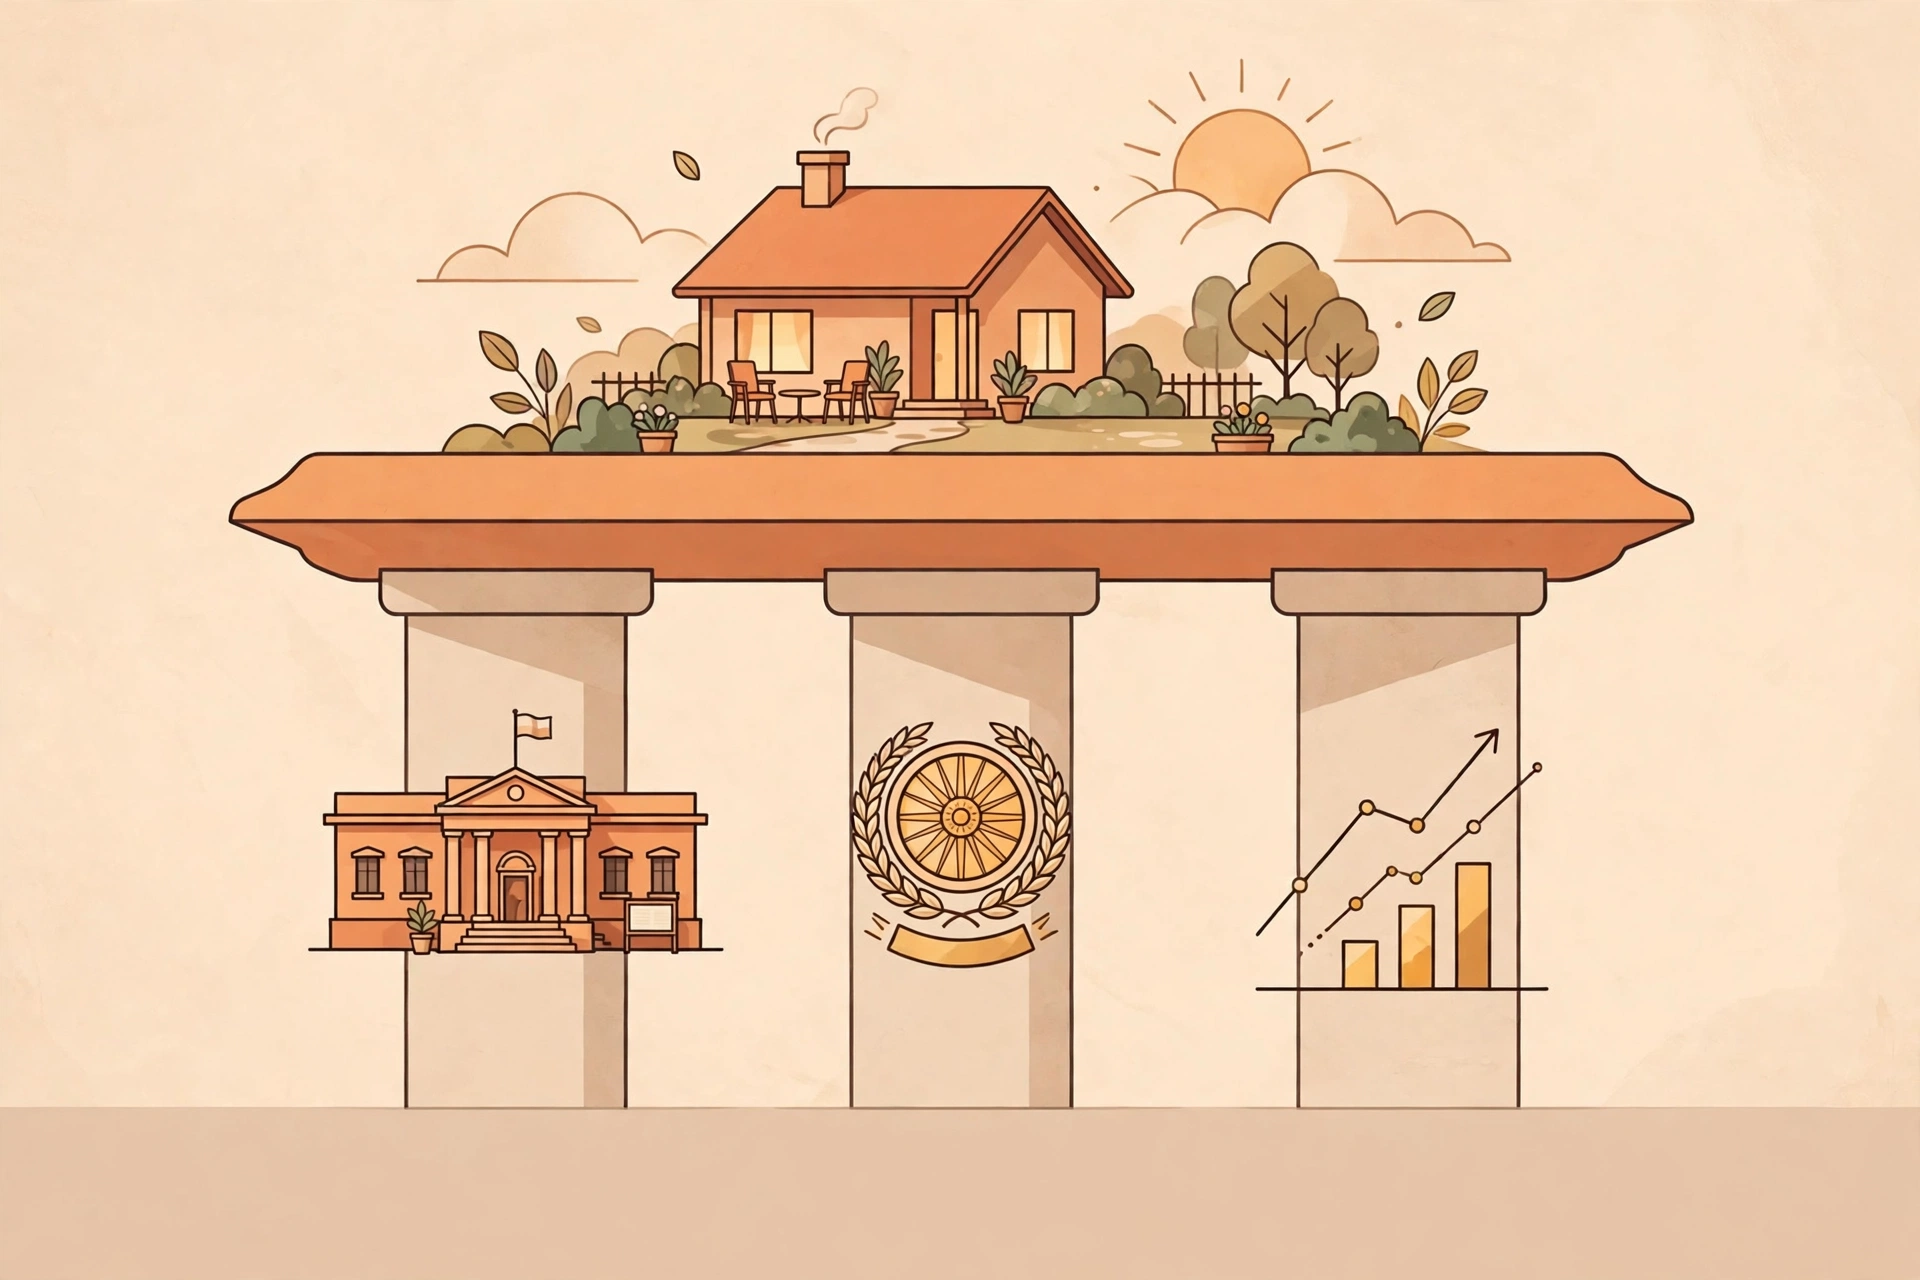
Most salaried employees already have a retirement engine running without realising it: the Employees’ Provident Fund. Every month, 12 percent of your basic salary goes into EPF from your side, and your employer contributes a similar amount, with a portion going to the pension scheme. The money earns a government-declared interest rate — around 8 percent in recent years — and it is tax-free on withdrawal if you have completed five years of service. Do not withdraw EPF when changing jobs to fund a holiday or a car. Transfer it instead. That pot, left alone for 30 years, often becomes one of the largest single chunks of a salaried person’s retirement wealth, precisely because it grows untouched.
The National Pension System is the other structured option worth knowing. NPS lets you invest in a mix of equity, corporate bonds, and government securities, with very low fund management charges, and it gives an extra tax deduction of up to Rs 50,000 a year under section 80CCD(1B) over and above the usual 80C limit. It locks your money in until 60, with partial withdrawal rules, and at retirement you use part of the corpus to buy an annuity — a monthly pension — while the rest can be withdrawn. NPS will not make you rich on its own, but as a disciplined, low-cost second pillar next to EPF, it is hard to beat.
Mutual funds through SIPs are the flexible third pillar. Unlike EPF and NPS, you control the amount, you can pause or increase it, and you can choose funds that match your risk appetite. For retirement, equity-oriented funds make sense in your thirties, with the allocation to debt rising as you age. One caution: do not spread yourself across ten funds. Two or three good funds are plenty. More funds do not mean more diversification; they usually mean overlapping holdings and a portfolio you cannot be bothered to track.
A Simple Step-by-Step Plan on Rs 60,000–80,000 a Month
Take a salaried person, 32 years old, earning Rs 70,000 a month after tax. Rent is Rs 18,000, groceries and household costs run about Rs 15,000, transport and UPI spending on food and small purchases take another Rs 10,000, and an EMI plus insurance premiums account for Rs 10,000. That leaves roughly Rs 17,000 for saving. Here is how a sensible retirement plan could look on that budget, without pretending the person lives on air.
Step one: protect the basics first. Before investing aggressively, make sure term insurance and health insurance are in place, and keep three to six months of expenses — say Rs 1.5 to 3 lakh — in a liquid fund or savings account as an emergency fund. Investing without this cushion means the first crisis forces you to sell investments at the worst time.
Step two: let EPF do its job and add NPS on top. EPF is already coming out of the salary. Add an NPS contribution of Rs 4,000 to Rs 5,000 a month if the budget allows, using the auto-debit option so it happens before you can spend it.
Step three: start a monthly equity SIP of Rs 8,000 to Rs 10,000 for retirement, in one or two broad funds. Treat this as a bill, paid on salary day, not as whatever is left at month-end. Month-end money has a habit of disappearing into food delivery and sale-season shopping.
Step four: raise the SIP by 10 percent every year, or at least every time you get a raise. A Rs 10,000 SIP growing by 10 percent annually becomes Rs 11,000 next year and roughly Rs 16,000 in five years — and because your salary is also growing, it rarely feels like a sacrifice. This single habit, the annual step-up, is what turns a decent plan into a strong one.
Step five: review once a year, not every week. Check whether the SIPs are running, whether your emergency fund is intact, and whether any big life change — marriage, a child, a home loan — means the plan needs adjusting. Ignore daily market news. A retirement plan is judged over decades, and checking it daily only creates anxiety and bad decisions.
Mistakes to Avoid in Your 30s
The biggest mistake is waiting for a “better time” — a bigger salary, a bonus, a loan-free month. There is rarely a perfect month, and each year of waiting costs more than the last, as the comparison between Priya and Rahul showed. Start small if you must, but start.
The second mistake is raiding long-term investments for short-term wants. Breaking a SIP to fund a vacation or a phone upgrade feels harmless once, but it breaks the compounding chain and, worse, it teaches you that retirement money is available for spending. Keep a separate, smaller fund for wants, and let the retirement pot stay boring and untouched.
The third mistake is putting everything into real estate or gold and calling it retirement planning. A house is a place to live, not a pension — selling it in retirement means finding somewhere else to live. Gold has a role as a small hedge, but it generates no income and has long flat periods. A retirement plan needs assets that grow and can be drawn down gradually, which is why EPF, NPS, and mutual funds sit at the centre of it.
The fourth mistake is ignoring tax, but only in the sense of letting it drive every decision. Tax-saving products like ELSS funds or PPF have their place — PPF in particular is a fine, safe, tax-free long-term option — but a product bought only for a deduction in March is rarely the best retirement tool. Choose the investment first, then check the tax treatment, not the other way round.
None of this requires you to become a finance expert or to spend your weekends tracking markets. It requires a salary-day system: insurance in place, an emergency cushion, EPF running, an NPS contribution if it fits, and a SIP that steps up each year. If you set that up in your thirties and mostly leave it alone, your sixty-year-old self will not need a miracle. They will just need the money to be there — and thanks to three decades of quiet compounding, it should be.