Yes, you can start a SIP with ₹500 a month. That is not a marketing line. Most mutual funds in India now let you begin with ₹500, some even with ₹100, and that small monthly amount is genuinely enough to get you into the habit of investing. If you have been putting it off because you thought investing was only for people earning a big salary, this is your starting point. You do not need a lump sum, a demat account, or any deep knowledge of the stock market. You need a bank account, a PAN card, and a decision to let a small amount leave your account every month before you get a chance to spend it.
People often ask whether ₹500 is too little to matter. On its own, in one month, it is. Over years, it behaves very differently, because a SIP is less about the amount and more about the rhythm. The same ₹500 that disappears into chai, auto rides, and a streaming subscription can quietly become a real sum if it goes into an investment every month without fail. This guide walks through what a SIP actually is, why small amounts still work, how to pick a first fund without spending weeks on research, and how to set the whole thing up in an afternoon.
What a SIP Actually Is
A Systematic Investment Plan, or SIP, is simply a way of investing a fixed amount in a mutual fund at regular intervals, usually every month. Instead of trying to guess the right day to invest a large amount, you put in the same sum on roughly the same date each month. The fund uses your money to buy units of the scheme. When markets are up, your ₹500 buys fewer units. When markets are down, the same ₹500 buys more units. Over time, that averaging smooths out the ups and downs, and it takes the pressure off trying to time the market, which even experienced investors get wrong.
Think of it like a recurring deposit, except the returns are not fixed and the money goes into market-linked investments such as shares or bonds, depending on the fund you choose. That means the value of your investment will move up and down, sometimes for months at a stretch. It also means the long-term returns can be higher than a fixed deposit, though nothing is guaranteed. A SIP is not a product by itself. It is a method of investing in a mutual fund, and the fund you pick decides where your money actually goes.
The money leaves your bank account through an auto-debit mandate, much like a UPI autopay for a subscription. You pick a date, say the 5th of every month, ideally a day or two after your salary comes in. Once the mandate is active, you do not have to remember anything, which is the whole point: most SIPs fail because the person stops, not because the fund was bad.
Why ₹500 a Month Still Works
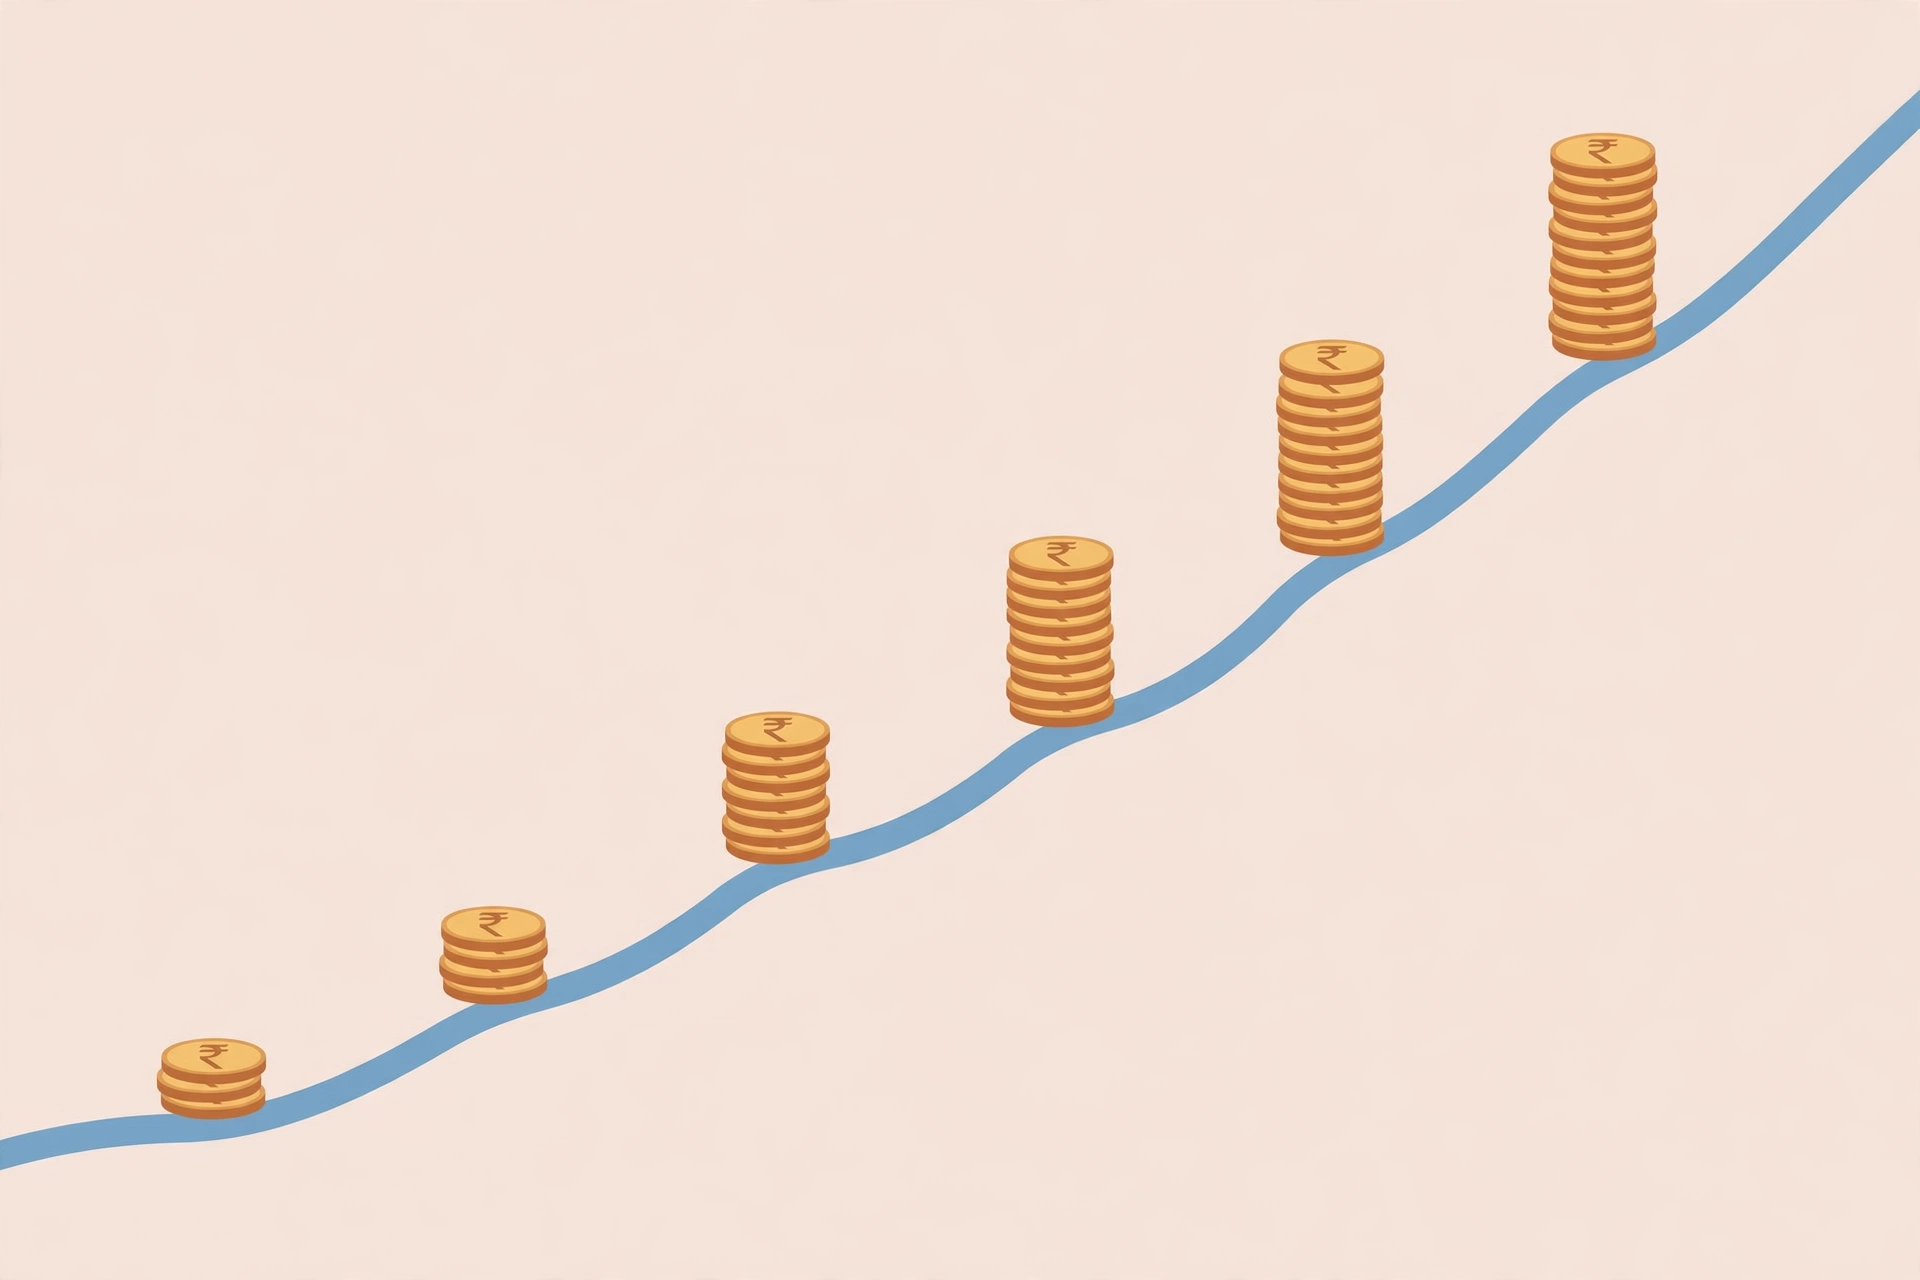
The reason small SIPs work is compounding. Returns earned in one year stay invested and start earning returns of their own in the next year, and so on. In the early years the growth looks slow, almost boring. A ₹500 SIP does not feel like it is going anywhere in the first year or two. Then, gradually, the curve bends upward, because the base on which returns are earned keeps getting bigger. Time does more heavy lifting here than the monthly amount does.
To see this clearly, look at what ₹500 a month could become at an assumed long-term return of 12% a year. That figure is only an illustration, not a promise. Mutual fund returns vary, and equity funds in particular can go through flat or negative years. The point of the table is to show the shape of growth over time, not to predict what you will actually get.
| Time period | Total invested | Illustrative value at 12% a year |
|---|---|---|
| 5 years | ₹30,000 | About ₹41,000 |
| 10 years | ₹60,000 | About ₹1,16,000 |
| 15 years | ₹90,000 | About ₹2,52,000 |
| 20 years | ₹1,20,000 | About ₹5,00,000 |
Notice how the gap between what you put in and what it grows to widens with time. After five years the difference is modest. After twenty years, the illustrative value is more than four times the money invested. That is why starting early matters more than starting big. A 23-year-old putting in ₹500 a month has something a 33-year-old putting in ₹1,000 a month cannot buy back: ten extra years of compounding. If your income grows later, you can step up the SIP to ₹1,000, ₹2,000, or ₹5,000 a month. Many funds let you increase the amount or start a second SIP whenever you want. The first step is simply to begin.
Picking Your First Fund Without Overthinking
The fund universe can feel overwhelming. There are thousands of schemes, star ratings, past-return charts, and new fund offers (NFOs) advertised every month. For a first SIP, you can ignore almost all of that. Your job is to pick something simple, diversified, and cheap, and then leave it alone. Two sensible starting points for most beginners are an index fund and a flexi-cap fund, and understanding the difference between them is enough to choose.
An index fund simply tracks a market index such as the Nifty 50 or Sensex. It buys the same large companies in roughly the same proportion as the index, without a fund manager trying to pick winners. The cost is low, often an expense ratio well under 0.5% a year, and the performance is close to the broader market. A flexi-cap fund, on the other hand, is actively managed. Its manager can invest across large, mid, and small companies as opportunities change. It may beat the market or lag it, and it usually costs more, often around 1% a year or more for a regular plan. Neither is right or wrong. An index fund is the simpler, lower-cost default for a first SIP. A flexi-cap fund suits someone who wants active management and is comfortable paying for it.
You will also see the same fund offered as a direct plan and a regular plan. The difference is straightforward. A direct plan is bought straight from the fund house or an investment platform, with no distributor commission, so its expense ratio is lower and slightly more of your money stays invested. A regular plan goes through a distributor or agent who earns a commission built into the expense ratio. If you are comfortable doing a little reading yourself, a direct plan usually works out cheaper over the years. If you genuinely want someone to guide you and answer questions, a regular plan through a trusted adviser is a fair trade. What matters less than this choice is actually starting and staying invested.
A few cautions will save you trouble. Do not pick a fund only because it topped the return charts last year. Last year’s winner is often next year’s average performer, and chasing it means buying after the good run is over. Be wary of NFOs that promise a new theme or sector, because a brand-new fund has no track record and the theme may already be expensive by the time it reaches you. Check the expense ratio, make sure the fund is diversified rather than concentrated in one sector, and prefer a fund that has been around for several years with a steady, unexciting record over one with a spectacular but short history. Boring is good for a first fund.
How to Set Up Your SIP
Setting up a SIP takes less time than most people expect, usually under an hour once your documents are ready. Before you invest, make sure your basic safety net is in place. A SIP is for long-term money, not for the cash you would need if you lost your job or faced a medical bill. If you do not have a small emergency cushion, build that first, and this guide to building an emergency fund in India explains how much to keep aside and where to park it. Once that is sorted, investing ₹500 a month will not leave you stretched in a bad month.
Next comes KYC, which is a one-time identity verification required for all mutual fund investors in India. You need your PAN card, your Aadhaar, and a bank account in your name. Most fund houses and investment apps let you complete e-KYC online with an OTP on your Aadhaar-linked mobile number and a short video verification. If your KYC is already done, you may be able to skip straight to the investment step.
Once KYC is complete, you can invest through the fund house’s own website or app, or through a registered investment platform. Search for the fund you picked, choose the direct or regular plan, select the SIP option, and enter ₹500 as the monthly amount. Then pick a date and set up the auto-debit mandate, which authorises the fund to pull the amount from your bank account each month. This is usually done through net banking, UPI autopay, or a one-time mandate form, and it may take a few days to activate. Check that the first debit actually happens, and check your bank statement the following month to confirm the rhythm is set. After that, you mostly need to leave it alone.
Mistakes That Trip Up Beginners
Most SIP mistakes are not about picking the wrong fund. They are about behaviour, and they are easy to make because they feel sensible in the moment. Knowing them in advance makes them easier to resist when the market gives you a reason to act.
- Stopping the SIP when the market falls. A fall means your ₹500 buys more units, which is exactly when continuing helps most. Pausing in a dip locks in the worst timing.
- Chasing last year’s top fund. Returns rotate, and the fund that looked unbeatable last year may quietly underperform for the next three. A steady fund you can stick with beats a fashionable one you keep switching away from.
- Investing money you will need within a year. A SIP in an equity fund is not a savings account. If the money is for a fee due next semester or a trip next summer, keep it in a liquid fund or a bank deposit instead.
- Checking the value every day. Daily ups and downs say nothing about a ten-year plan, but they create the urge to act. A monthly or quarterly glance is plenty for a long-term SIP.
- Starting five SIPs at once. One or two diversified funds are enough to begin. Too many funds overlap, complicate tracking, and dilute the habit you are trying to build.
When a SIP Is NOT the Right Parking Place
A SIP earns its keep for goals that are several years away: a house down payment in eight years, a child’s education, or retirement decades down the line. For those long horizons, the ups and downs have time to even out, and compounding has room to work. That is why SIPs fit so naturally into long-term planning, and if retirement is on your mind, this guide to retirement planning in your 30s shows how small monthly amounts fit into a much longer plan.
But a SIP in an equity fund is a poor parking place for short-term money. If you are saving for a phone in six months, a course fee next year, or a wedding in the family, the market could easily be down when you need the money. Selling at a loss because a deadline arrived is a painful and avoidable outcome. For goals under three years, a recurring deposit, a liquid fund, or a short-duration debt fund is usually a better fit, even though the returns are lower. The goal of short-term savings is to be there when needed, not to grow aggressively.
Emergency money follows the same logic. Your emergency fund should sit in a savings account or a liquid fund you can reach within a day, not in an equity SIP whose value might be down 15% in the week you need it. Mixing the two jobs, growth and safety, in one pot usually means the money fails at one of them. Keep the emergency cushion separate, keep short-term goals separate, and let the SIP do the one job it is good at: building wealth slowly over years.
Starting Small, Staying Put
If you take one thing from this guide, let it be this: the amount matters less than the start. Open the app or the fund website this week, finish your KYC if it is pending, pick one simple fund, and set a ₹500 SIP for a date just after your salary arrives. Then resist the urge to tinker. You can review the fund once a year, step up the amount when your income rises, and add a second SIP for a different goal when you are ready. None of that needs to happen in the first month.
There will be months when the SIP feels pointless, when ₹500 seems too small to change anything, and when the market news makes you want to stop. That feeling is part of the process, not a sign that something is wrong. The people who end up with meaningful sums from SIPs are rarely the ones who picked the cleverest fund. They are the ones who kept a modest amount going through dull years and bad years alike, increased it when they could, and gave time a chance to do its quiet work. Your ₹500 a month is a perfectly respectable beginning, and the best day to set it up is the next payday.