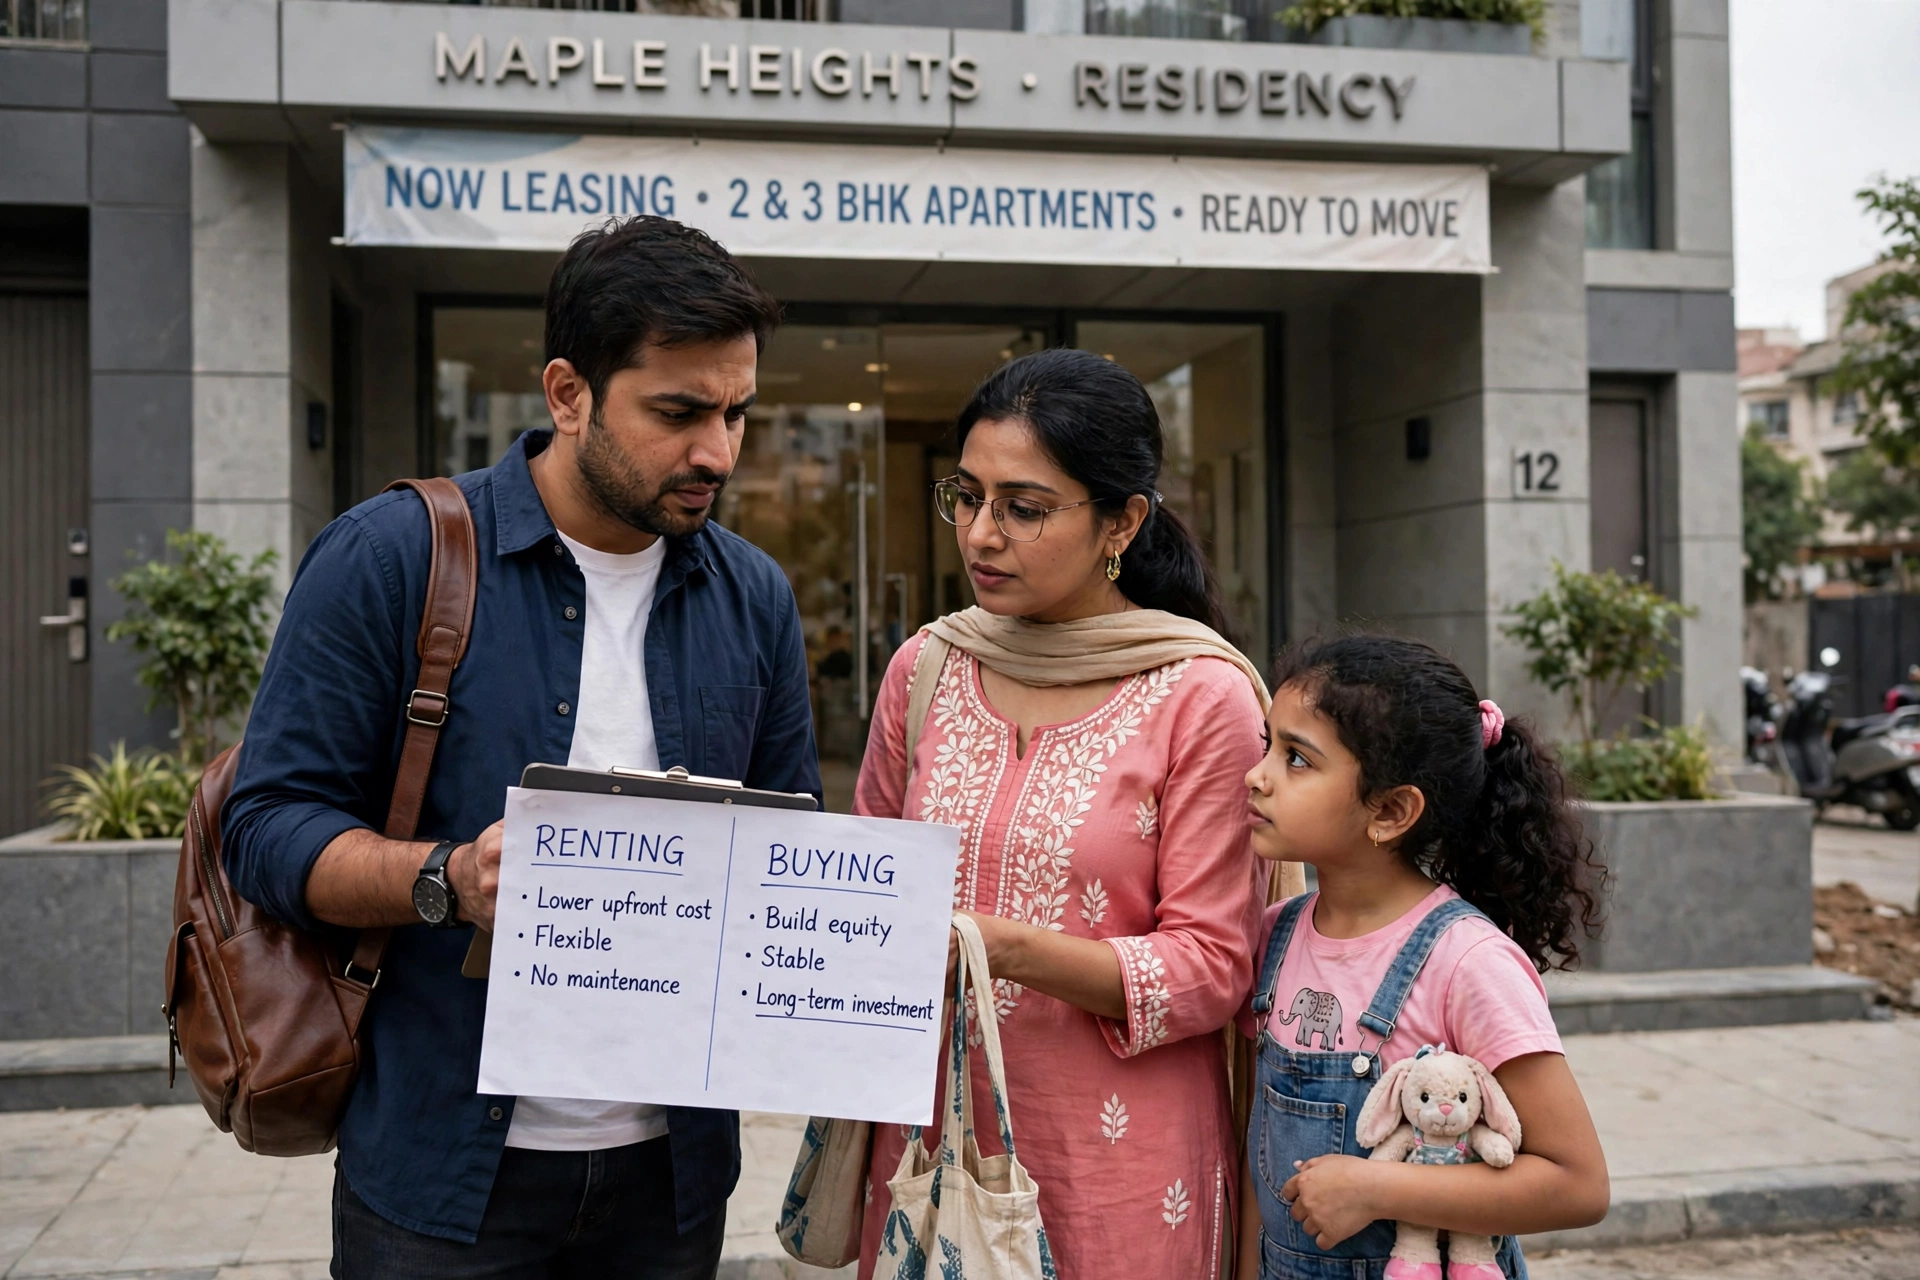
Rent vs buy house India is a question almost every working family in India faces at some point, usually when rent starts feeling like money thrown away, or when a builder’s brochure makes buying look easy. The honest answer comes early, because it saves a lot of confusion later: neither renting nor buying is always right. It depends on the numbers in your city, and on how long you will actually stay in that home.
A flat that makes complete sense to buy in Indore can be a poor deal in Mumbai. A home you plan to live in for fifteen years is a very different decision from a home you might leave in three years for a job change. That is why this decision needs maths first, and emotion second. Not the other way round.
The Short Answer, Before the Details
Buying usually starts to win when you stay put for a long time, your monthly outgo is manageable, and you have enough savings left after the down payment. Renting usually wins when you need flexibility, your city has very high property prices compared with rents, or buying would stretch your monthly budget to breaking point.
Both sides have costs that do not show up in the headline number. The rest of this article works through those costs with one clear example, so you can replace it with your own city’s figures.
One Example to Make the Maths Visible
Take a two-bedroom flat priced at ₹80 lakh. These are illustrative, approximate figures, not a quote from any bank or builder, but they are close enough to how the numbers usually behave. You pay 20% as a down payment, which is ₹16 lakh. The remaining ₹64 lakh comes as a home loan at roughly 8.5% interest for 20 years. The approximate EMI works out to around ₹55,500 per month.
Over 20 years, that EMI adds up to roughly ₹1.33 crore. Out of that, about ₹69 lakh is interest alone. That is the first surprise for many buyers. You did not buy an ₹80 lakh flat for ₹80 lakh. You bought it for the down payment, plus registration and other upfront charges, plus twenty years of EMIs.
None of this means buying is wrong. It means the comparison cannot be EMI versus rent alone. The starting point has to be honest: the loan costs far more than the price on the brochure.
What Renting the Same Flat Looks Like
Now suppose a similar flat in the same area rents for about ₹20,000 per month. At first glance, the gap looks huge: ₹20,000 rent against a ₹55,500 EMI. Renting looks like an easy win, and in the early years, on monthly cash flow alone, it is.
Rent does not stay at ₹20,000, though. If it rises by about 5% a year, which is common in many Indian cities, it becomes roughly ₹21,000 in the second year, about ₹25,500 after five years, and close to ₹50,000 a month by year twenty. Over the full twenty years, total rent paid would be roughly ₹79 lakh, again as an illustrative figure. That is still less than the total EMI outgo, but the gap narrows a lot over time.
The renter also keeps one big advantage: the ₹16 lakh that a buyer puts into a down payment stays available, instead of being locked into one flat. That cash, and the monthly difference between rent and EMI in the early years, is where the real comparison gets interesting.
| Item | Buying (illustrative) | Renting (illustrative) |
|---|---|---|
| Upfront cash | ₹16 lakh down payment, plus stamp duty and registration | Deposit, usually a few months’ rent, refundable |
| Monthly payment, year one | About ₹55,500 EMI, plus maintenance | About ₹20,000 rent |
| Payment in year twenty | EMI still about ₹55,500, loan ends | Rent close to ₹50,000, and still going |
| What you own at the end | A flat, if the loan is fully repaid | No property, but cash stayed flexible |
The Down Payment Has a Cost Too
People often treat the down payment as money that simply moves from a bank account into a flat. It does, but it also stops earning anything elsewhere. That missed growth is called opportunity cost, and it matters more than most buyers expect.
Take that ₹16 lakh again. If it stayed invested and grew at an illustrative rate of around 10% a year for twenty years, it could grow to roughly ₹1.08 crore. That is an approximate, illustrative calculation, and actual returns would vary a lot. The point is not the exact final figure. The point is that ₹16 lakh today is not a small amount, and locking it away has a real price.
This does not mean you should never use savings for a home. A home is also a place to live, not only an investment. But leaving this side out makes buying look cheaper than it is.
The Costs Buyers Often Forget
Beyond the EMI, a homeowner pays for things a tenant usually does not. Stamp duty and registration charges can add roughly 5% to 7% of the property value in many states, which on an ₹80 lakh flat means another ₹4 lakh to ₹5.6 lakh upfront, approximately. Society maintenance charges of ₹3,000 to ₹5,000 a month are common in many apartment complexes, and they rise over time.
Property tax, usually a few thousand to twenty thousand rupees a year depending on the city and flat size, is the owner’s bill. So are major repairs: a leaking roof, repainting, plumbing work, or replacing fittings. A tenant can call the landlord for many of these. An owner pays, arranges, and waits for the work to be done.
Smaller costs add up too: home insurance, furnishing a bare flat, and moving. Together, they explain why the true monthly cost of owning is always higher than the EMI on the loan statement.
Home Loan Tax Benefit, in Outline Only
Home loans do come with tax benefits, but they are not as simple as they once sounded, and they should not be the main reason to buy. In outline, under the old tax regime, interest paid on a home loan for a self-occupied house has a deduction limit, and principal repayment can fall under a separate deduction limit. Under the new tax regime, which many taxpayers now use, these particular benefits generally do not apply in the same way.
The exact benefit depends on your income, regime choice, and loan details, so check your own tax situation before counting on it. Do not assume the tax saving will wipe out the interest cost. If buying only works because of an assumed tax saving, the maths is probably too tight.
For a fuller sense of how banks judge whether you can afford a loan in the first place, this guide on home loan eligibility walks through the factors lenders usually look at.
How Long Must You Stay for Buying to Win?
This is the question that ties everything together. In the first few years, buying usually loses on pure numbers. The upfront charges are fresh, the EMI is mostly interest, and very little of the loan principal has been repaid. If you sell early, you may also face selling costs, and the flat may not have risen enough to cover what you paid.
As the years pass, the balance shifts. The EMI stays fixed while rent keeps rising. More of each EMI starts going towards principal. The upfront charges get spread over more years of living there. In many Indian cities, buying starts to look better after roughly seven to ten years of staying in the same home, though this varies a lot by city.
In cities where prices are very high compared with rents, like parts of Mumbai or central Bengaluru, break-even can take longer. Where prices are lower, it can be shorter. That is why a rule borrowed from another city can mislead you.
Job mobility matters here too. If your work could move you to another city in two or three years, renting keeps that move simple. Selling a flat, or managing it from another city as a landlord, is a second job in itself. Buying makes most sense when you have a fair degree of confidence about staying in that city, and in that home, for a long stretch.
Four Checks Before You Buy
First, check your emergency fund. After paying the down payment, stamp duty, registration, and moving costs, you should still have enough savings to cover several months of expenses. A home that leaves you with nothing in the bank is a risk, not a safety net. This guide on how much emergency fund you really need and where to keep it is a useful place to work out that cushion before you commit.
Second, check the EMI against your take-home pay. As a rough guide, keeping the EMI comfortably below about 40% of take-home pay leaves room for food, transport, school costs, medical bills, and the maintenance charges that come with owning. If the EMI eats up half your monthly income, one unexpected expense can turn into a crisis.
Third, check job and city stability. Buying suits a settled phase of life: a stable job, a city you expect to stay in, and family plans that fit that home for years. If a transfer, a career change, or a move abroad is likely soon, waiting is often the calmer choice.
Fourth, look at total cost, not just EMI. Add maintenance, property tax, insurance, and a small monthly amount for repairs. Compare that total with rent for a similar flat. If the total is still within your comfort range, and the other checks pass, buying becomes a much stronger case.
When Renting Is the Smarter Choice
Renting has real strengths that get lost when it is described only as money down the drain. It needs far less upfront cash, which leaves your savings free for emergencies, future plans, or other goals. It gives you flexibility to move for a better job, a shorter commute, or a change in family size, without selling a property.
It also caps your housing risk. If the building needs major repairs, or the area changes in a way you do not like, a tenant can move at the end of the lease. An owner cannot, at least not quickly or cheaply. For young professionals, couples still figuring out where they want to settle, and anyone whose income is not yet steady, that flexibility is worth a lot.
Renting works best when the money saved is kept aside and allowed to grow, rather than spent. That discipline is the quiet part of the renting case that nobody puts in a brochure.
Putting It Together for Your Own Decision
Start with your city’s actual numbers, not a national average. Find the price of the kind of flat you would buy, the rent for a similar flat in the same area, and a realistic loan EMI. Add stamp duty, maintenance, and tax. Then ask how long you will stay. If the answer is under five years, renting will usually come out ahead. If it is ten years or more, and the monthly total fits comfortably, buying starts to earn its case.
Also ask what kind of life you want. Some people value the stability of their own walls and the freedom to renovate. Others value the freedom to move, lighter monthly outgo, and cash that stays within reach. Both are reasonable, as long as the choice is made with eyes open.
Run the numbers for your flat, your rent, and your timeline, and let them speak before you sign anything. A home is the largest purchase most of us will ever make. It deserves a decision made on its full cost, not only on the EMI, and not only on the rent. This is general educational information to help you compare the two paths, not advice for your personal situation, so take the time to work through your own figures and, if needed, talk to a qualified professional about the loan and tax details.