Saving money is one of those things we all know we should do, but actually doing it every month can be difficult.
At the beginning of the month, you may decide that you’ll save a good amount from your salary or pocket money. But then the usual expenses start coming in. Bills, food, shopping, travel, subscriptions, small online purchases—and suddenly, there’s hardly anything left to save.
This is where a simple habit like saving ₹100 a day can make a difference.
₹100 may not sound like a lot of money. In fact, you might spend ₹100 without thinking twice. But what happens when you make saving that ₹100 a daily habit?
The calculation is simple:
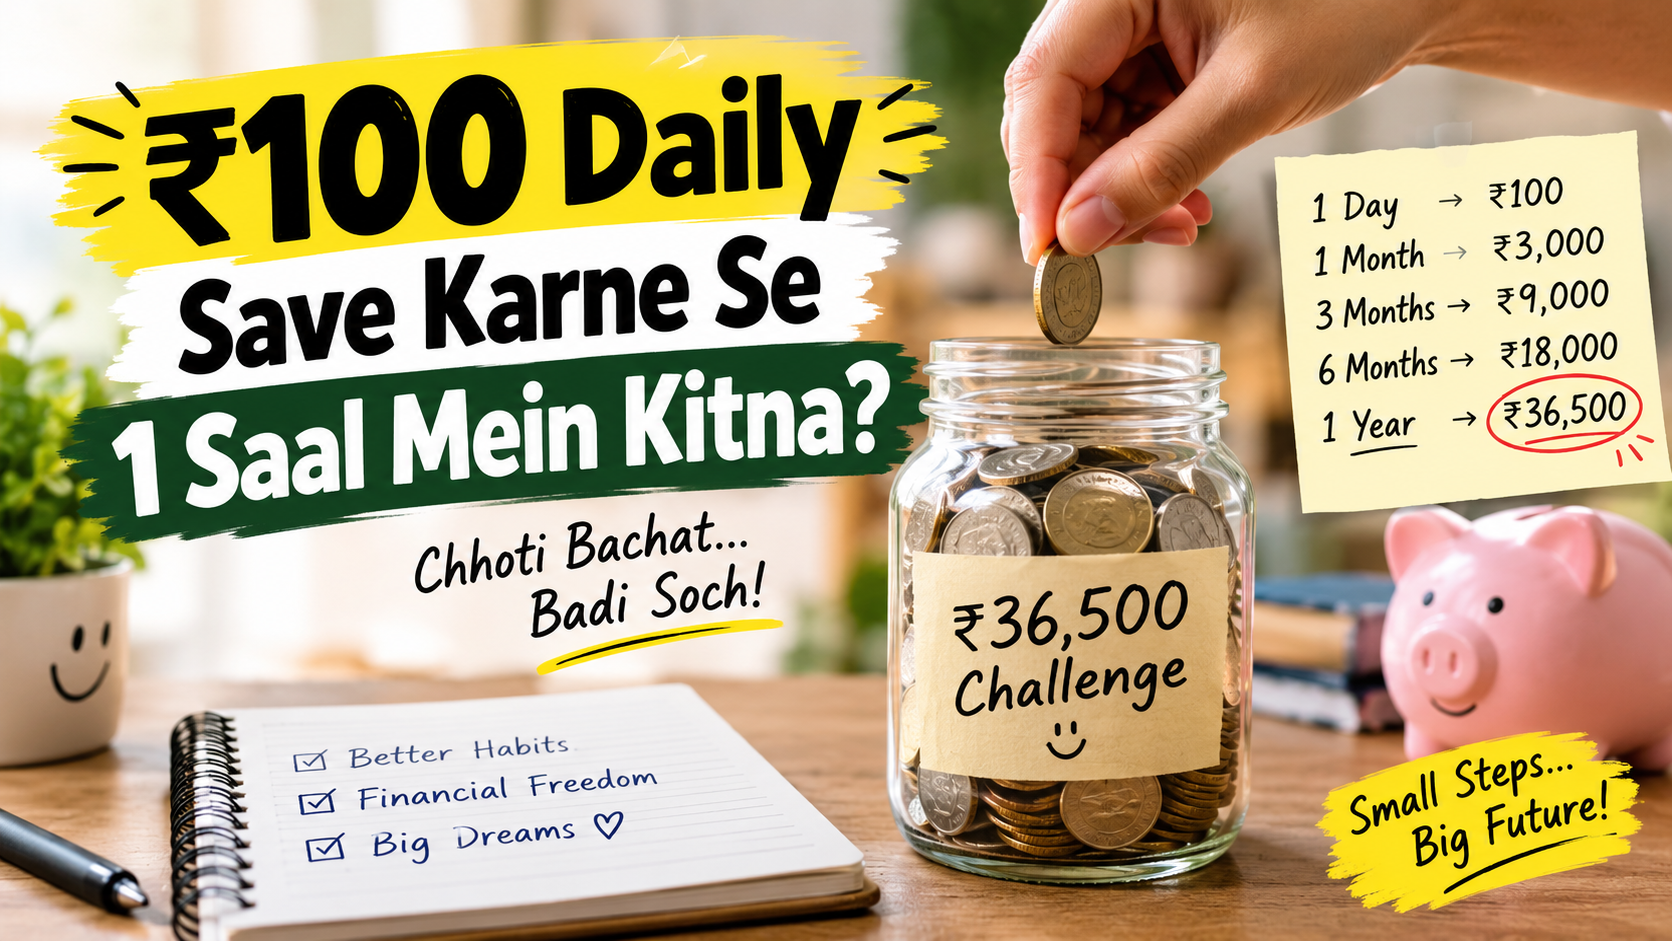
₹100 × 365 days = ₹36,500
So, if you manage to save ₹100 every single day for one year, you’ll have ₹36,500 at the end of the year.
But there’s something more important here than the number itself.
You’re building a habit of saving.
And that habit can become much more valuable over time.
Why Start With Just ₹100?
One of the biggest mistakes people make when they decide to save money is setting a goal that is too difficult to maintain.
For example, someone might say, “I’ll save ₹15,000 every month.”
It sounds good, but if their income is limited and their expenses are already high, the plan may last only a few weeks.
₹100 feels different.
It’s small enough that many people can realistically try it without completely changing their lifestyle.
The idea isn’t to become financially successful in one day. It’s to make saving so simple that you can keep doing it.
Think about it this way.
You don’t need to find an extra ₹36,500 today.
You only need to find ₹100 today.
Tomorrow, you do it again.
That’s what makes the challenge manageable.
Let’s See How Fast ₹100 Adds Up
The amount may seem small when you look at it day by day. But once you start adding it together, the picture changes.
After one week:
₹100 × 7 = ₹700
After one month of 30 days:
₹100 × 30 = ₹3,000
After three months:
₹9,000
After six months:
₹18,000
And after a full year:
₹36,500
That’s the interesting part about small savings. You don’t notice the amount growing every single day, but after a few months, the difference becomes much easier to see.
Where Can You Find ₹100 Every Day?
This is probably the question most people will ask.
“Okay, but where am I supposed to get that extra ₹100?”
The answer may already be in your daily spending.
Think about the small purchases you make without planning.
Maybe you order something because you’re too tired to cook. Maybe you buy snacks while you’re outside. Maybe you add something unnecessary to your online cart because there’s a discount.
None of these expenses necessarily seem like a big deal on their own.
But when they happen regularly, they can add up.
For example, suppose you spend ₹100 on an unnecessary purchase three or four times a week.
You could start by replacing just one of those purchases with saving.
You don’t have to stop enjoying life.
The goal is simply to become more conscious about where your money goes.
Small Expenses Are Easy to Ignore
This is one of the most important things to understand about personal finance.
Large expenses usually get our attention.
If you’re about to spend ₹20,000 on something, you’ll probably think about it carefully.
But ₹50 or ₹100?
Most people don’t think twice.
That’s why small expenses can quietly affect your budget.
Imagine spending an extra ₹100 every day.
At the end of 30 days, that’s approximately ₹3,000.
Over a year, it’s ₹36,500.
Again, this doesn’t mean spending ₹100 is always bad.
Sometimes that ₹100 may be completely worth it.
The point is to know whether you’re spending it intentionally or simply because it’s become a habit.
Make Saving Automatic
If you know you’re going to forget about the challenge after a few days, don’t depend completely on motivation.
Make the process easier.
You could transfer money regularly into a separate savings account or use whatever saving method is suitable for you.
Another simple option is to think monthly instead of daily.
If your target is ₹100 per day, you can aim for roughly:
₹3,000 per month
Instead of making 30 separate decisions, you can plan your monthly saving amount in advance.
This is often easier for people who receive a salary or regular income.
The important thing is consistency.
Keep Your Savings Separate
Here’s a simple trick that can make saving much easier.
Don’t keep your savings mixed with the money you use for everyday spending.
If you see extra money sitting in your regular account, you may eventually think:
“I can use this. I’ll save again next month.”
And that’s how savings disappear.
Keeping your savings separate creates a small mental barrier between your spending money and your goal money.
You could even name your goal something motivating, such as:
₹36,500 Challenge
Watching that number increase month after month can be surprisingly satisfying.
What Can You Do With ₹36,500?
Now comes the more interesting question.
Suppose you’ve successfully saved ₹36,500.
What should you do with it?
There’s no single answer because everyone’s financial situation is different. But there are several sensible possibilities.
Build an Emergency Fund
Unexpected expenses can appear at the worst possible time.
A repair, urgent travel, an unexpected bill, or a temporary income problem can put pressure on your finances.
Having some money set aside can give you breathing room.
₹36,500 may not cover every emergency, but it can be a meaningful start.
If your expenses are higher, you can continue building your emergency savings beyond this amount.
Save for a Specific Goal
Maybe you’re saving for a laptop, education, a trip, a course, or another important purchase.
Having a dedicated fund means you don’t have to depend entirely on credit or borrowing when the expense arrives.
The more specific the goal, the easier it can be to stay motivated.
Instead of saying:
“I need to save money.”
Try:
“I’m saving ₹36,500 for my emergency fund.”
A clear goal gives your saving a purpose.
Consider Long-Term Investing
Once you’ve built appropriate emergency savings and have a clear understanding of your financial situation, you may also consider investing for long-term goals.
But remember that saving and investing aren’t the same thing.
Money kept for short-term needs generally needs accessibility and stability.
Investments can fluctuate in value and involve different levels of risk.
So don’t invest money simply because you feel you have to make it grow quickly.
Understand the investment first and make sure it fits your goal and time horizon.
What If You Miss a Day?
Don’t panic.
You’re trying to build a long-term habit, not pass an exam.
If you save ₹100 for ten days and then miss one day, you haven’t failed.
Just continue the next day.
One missed day isn’t the problem.
Giving up completely because of one missed day is the bigger problem.
This mindset applies to almost every financial habit.
There will be months when expenses are higher than usual. There may be unexpected situations. Your income may change.
The goal is to return to the habit when you can.
Start With 30 Days
If the idea of saving for 365 days sounds difficult, don’t think about the entire year.
Start with just 30 days.
Your first goal:
₹100 × 30 = ₹3,000
That’s it.
Don’t worry about the next 11 months yet.
Complete the first month.
Then start another 30-day challenge.
After three months, you’ll have around ₹9,000.
After six months, around ₹18,000.
Eventually, you may look back and realize you’ve built a habit that once seemed difficult.
Track Your Progress
Tracking your savings doesn’t need to be complicated.
You can use a notebook, spreadsheet, calendar, or notes app.
Every time you save ₹100, mark it.
For example:
Day 1 — ₹100 ✓
Day 2 — ₹100 ✓
Day 3 — ₹100 ✓
Day 4 — ₹100 ✓
It may seem childish at first, but seeing your progress can actually make the process more motivating.
You can also check your total at the end of every month.
Ask yourself:
How much did I save?
Where did I save the most?
Which expenses could I have avoided?
Was ₹100 comfortable, or should I adjust the target?
These small reviews can teach you a lot about your spending habits.
Once ₹100 Becomes Easy, Increase It
Here’s where the challenge can become even more interesting.
After saving ₹100 daily for a while, you may realize that the amount isn’t as difficult as you expected.
If your income and expenses allow it, you could gradually increase your target.
For example:
₹100 per day = ₹36,500 per year
₹200 per day = ₹73,000 per year
₹300 per day = ₹1,09,500 per year
The point isn’t that everyone should save ₹300 every day.
Everyone’s financial situation is different.
The lesson is that increasing your saving rate can have a significant impact over time.
Even an extra ₹50 a day makes a difference.
Don’t Try to Save Everything at Once
Personal finance doesn’t have to be extreme.
You don’t need to stop going out with friends.
You don’t need to avoid every small pleasure.
You don’t need to feel guilty every time you spend money.
A healthy financial plan should leave room for normal life.
The goal is to spend consciously.
If you really enjoy your morning coffee and it fits comfortably into your budget, that’s your choice.
But if you regularly spend money on things you don’t even value, that’s where you may have an opportunity to save.
It’s not about saying “no” to everything.
It’s about deciding what deserves your money.
Saving Is Only One Part of Personal Finance
Saving ₹100 a day is a great starting habit, but don’t stop there.
As your financial knowledge grows, you should also learn about:
- Budgeting
- Emergency funds
- Debt management
- Credit scores
- Insurance
- Investing
- Mutual funds
- Retirement planning
- Increasing your income
Saving helps you create a financial base.
Learning how to manage and grow your money can help you make better decisions in the future.
The Real Benefit of the ₹100 Challenge
At the end of the year, you might look at your account and see ₹36,500.
That’s great.
But the bigger achievement is that you proved something to yourself:
You can consistently save money.
Once you learn that, you can apply the same habit to bigger goals.
Maybe next year your target becomes ₹50,000.
Then ₹75,000.
Eventually, you might aim for ₹1 lakh.
The amount can change.
The habit is what stays with you.
Final Thoughts
Saving ₹100 a day isn’t going to make someone rich overnight.
And that’s not what this challenge is about.
It’s about starting somewhere.
For many people, the hardest part of saving isn’t the mathematics. It’s developing the discipline to actually keep money aside instead of spending everything that comes in.
₹100 gives you a simple starting point.
If you save it consistently for a year, you can reach ₹36,500.
More importantly, you’ll have spent a year practicing one of the most useful financial habits: paying yourself first and being intentional with your money.
So don’t wait until you have a higher salary.
Don’t wait until next year.
Start with an amount that feels realistic.
For this challenge, that amount is just ₹100.
₹100 today may not change your life. But the habit you build by saving it every day can change the way you manage money for years to come.