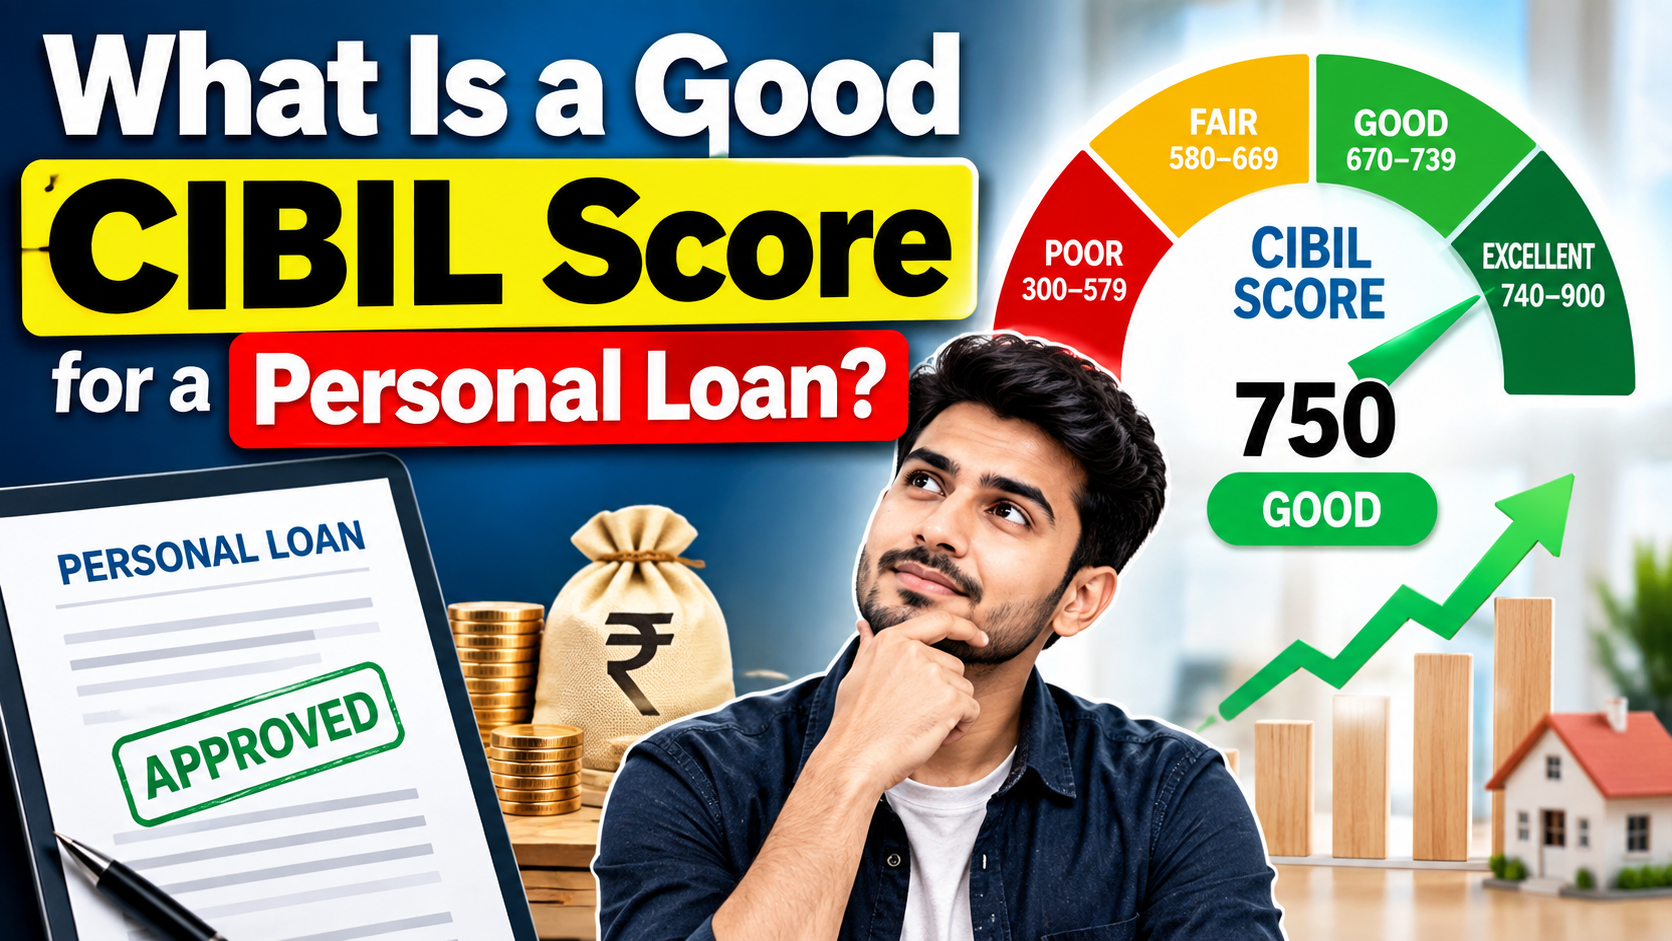
When you apply for a personal loan, one of the first things lenders may check is your CIBIL score. This three-digit number gives lenders an idea of how responsibly you have handled credit in the past. A higher score generally indicates a stronger credit history and may improve your chances of getting a personal loan on favorable terms.
But what exactly is considered a good CIBIL score for a personal loan? Is 700 enough? Do you need 750 or more? And what happens if your score is below 650?
In this guide, we explain the CIBIL score ranges, how lenders may interpret them, factors that affect personal-loan approval, and practical ways to improve your score before applying.
What Is a CIBIL Score?
A CIBIL score is a three-digit numerical representation of your credit history, generally ranging from 300 to 900. It is calculated using information in your credit report, including your borrowing and repayment history.
The score is associated with your credit profile and is used by banks and financial institutions as one of the factors when evaluating loan and credit-card applications.
A higher score generally suggests that you have demonstrated responsible credit behavior, such as making loan and credit-card payments on time and maintaining manageable outstanding debt.
However, your CIBIL score is not the only factor lenders consider when approving a personal loan.
What Is a Good CIBIL Score for a Personal Loan?
There is no single CIBIL score that guarantees personal-loan approval because every lender has its own eligibility criteria.
As a general guideline:
| CIBIL Score | General Credit Profile | Personal Loan Outlook |
|---|---|---|
| 750–900 | Very strong | Generally favorable |
| 700–749 | Good | Often acceptable |
| 650–699 | Fair | Approval may be possible |
| 600–649 | Low | Approval may be difficult |
| Below 600 | Poor | May be difficult with many lenders |
A CIBIL score of 750 or above is commonly considered a strong score for loan applications. Borrowers in this range may have access to a wider range of lending options, subject to income, employment, existing obligations and other criteria.
A score between 700 and 749 can also be sufficient for a personal loan with many lenders, although the interest rate and loan amount offered can vary.
If your score is below 700, getting a loan is not necessarily impossible. Some lenders may consider applications based on the overall credit profile and other eligibility factors.
Why Does Your CIBIL Score Matter for a Personal Loan?
Personal loans are generally unsecured loans, meaning they typically do not require collateral such as a property or vehicle.
Because there is no asset securing the loan, lenders pay close attention to the applicant’s credit history and repayment behavior.
Your CIBIL score can influence several aspects of a personal-loan application, including:
1. Loan Approval
A stronger credit score can indicate a history of responsible repayment. This may increase the likelihood of approval, provided the rest of your application meets the lender’s requirements.
2. Interest Rate
Creditworthy borrowers may qualify for more competitive interest rates. A lower interest rate can significantly reduce the total interest paid over the life of the loan.
For example, suppose you borrow ₹5 lakh for five years. Even a small difference in the interest rate can change the total repayment amount.
3. Loan Amount
Your credit profile, income and existing obligations can affect how much a lender is willing to lend.
Applicants with stronger profiles may have access to higher loan limits, although income and repayment capacity remain important.
4. Repayment Terms
Depending on the lender, your credit profile may also influence the terms offered, such as tenure and pricing.
Is 750 a Good CIBIL Score for a Personal Loan?
Yes. A CIBIL score of 750 or above is generally considered a strong credit score for loan applications.
However, having a 750+ score does not automatically guarantee approval.
For example, an applicant with a 780 score could still face difficulties if they have:
- A high existing debt burden
- Unstable income
- Insufficient employment history
- Recent loan defaults
- Too many outstanding loans
- A high credit-card utilization ratio
Therefore, your credit score should be viewed as one part of your overall financial profile.
Can I Get a Personal Loan With a 700 CIBIL Score?
A CIBIL score of 700 can still be workable for a personal loan.
Some lenders may consider applicants with scores around this level, particularly when other factors are strong.
For example, you may have a better overall application if you have:
- Stable employment
- Consistent monthly income
- Low existing debt
- A good repayment history
- Limited recent credit applications
- Reasonable credit-card utilization
However, the lender may offer different interest rates or loan amounts depending on its internal policies.
It is therefore important not to assume that a particular score guarantees a specific loan offer.
Can I Get a Personal Loan With a CIBIL Score Below 650?
It can be more difficult, but a low CIBIL score does not necessarily mean that every loan application will be rejected.
Some lenders may consider other aspects of your financial profile. However, borrowers with lower scores may face conditions such as:
- Higher interest rates
- Lower loan amounts
- Shorter repayment periods
- Additional eligibility requirements
- Higher scrutiny of income and employment
Before applying, it may be sensible to understand why your score is low and work on improving your credit profile.
Factors That Affect Your CIBIL Score
Your CIBIL score is influenced by several elements in your credit history.
1. Payment History
Your repayment history is one of the most important parts of your credit profile.
Missing loan EMIs or credit-card payments can negatively affect your credit history.
Making payments on time helps demonstrate responsible borrowing behavior.
2. Credit Utilization
Credit utilization refers to how much of your available revolving credit you are using.
For example, if your credit-card limit is ₹1 lakh and you regularly carry a balance of ₹80,000, your utilization is 80%.
High utilization may indicate that you are heavily dependent on available credit.
Keeping utilization at a manageable level can help maintain a healthier credit profile.
3. Credit History Length
A longer history of responsible credit usage can provide lenders with more information about your borrowing behavior.
Closing old credit accounts may sometimes reduce the length of your credit history, depending on how the information is reported.
4. Credit Mix
Your credit report may contain different types of credit, such as secured loans and unsecured loans.
A balanced credit profile can be viewed differently from one that consists entirely of unsecured borrowing.
However, you should not take a loan simply to increase your credit mix.
5. New Credit Applications
Applying for several loans or credit cards within a short period can result in multiple hard inquiries on your credit report.
A large number of recent applications may make lenders examine your credit profile more closely.
How Much CIBIL Score Is Needed for a ₹5 Lakh Personal Loan?
There is no fixed CIBIL score specifically required for a ₹5 lakh personal loan.
The lender may consider:
- CIBIL score
- Monthly income
- Employment status
- Employer profile
- Existing EMIs
- Credit-card balances
- Age
- Location
- Loan tenure
- Banking relationship
- Overall credit history
For example, someone earning ₹1 lakh per month with a strong repayment history may have a different borrowing capacity from someone earning ₹40,000 per month, even if both have similar CIBIL scores.
This is why credit score alone cannot determine how much personal loan you can get.
How to Improve Your CIBIL Score Before Applying for a Personal Loan
If your score is lower than you would like, improving it before applying may strengthen your application.
Pay All EMIs on Time
Set up automatic payments or reminders so you do not accidentally miss due dates.
Even one missed payment can negatively affect your credit history.
Keep Credit-Card Balances Under Control
Try not to consistently use a very high percentage of your available credit limit.
Paying your credit-card bill in full each month can also help you avoid unnecessary interest charges.
Avoid Applying for Multiple Loans
Do not submit loan applications to many lenders simultaneously just to compare offers.
Instead, research eligibility requirements first and apply selectively.
Check Your Credit Report
Review your credit report periodically for errors.
Look for:
- Incorrect personal details
- Loans that do not belong to you
- Incorrect payment information
- Duplicate accounts
- Incorrect outstanding balances
If you find inaccurate information, raise a dispute with the relevant credit bureau or lender.
Pay Down Existing Debt
Reducing outstanding balances can improve your overall financial position.
It can also reduce your monthly debt obligations, which may make a future loan application more comfortable from a repayment-capacity perspective.
How Long Does It Take to Improve a CIBIL Score?
There is no fixed timeline because improvement depends on the reason for the low score.
If the problem is high credit utilization, reducing outstanding balances may help over time as updated information is reported.
If your score has been affected by missed payments, rebuilding your credit history may take longer.
The most important factor is consistency.
Making timely payments month after month can gradually establish a stronger repayment record.
Does Checking Your CIBIL Score Reduce It?
Simply checking your own credit report or score is generally different from a lender making a hard inquiry during a credit application.
You should therefore monitor your credit report rather than avoid checking it out of fear that checking your own score will damage it.
Regular monitoring can help you identify errors or unexpected accounts early.
CIBIL Score vs Credit Report
These two terms are related but not identical.
Your CIBIL score is a numerical summary of your credit history.
Your credit report contains more detailed information, such as:
- Credit accounts
- Loan balances
- Repayment history
- Credit-card accounts
- Credit inquiries
- Account status
When preparing for a personal-loan application, reviewing the entire credit report can be more useful than looking at the score alone.
What Other Factors Do Banks Consider?
Even an excellent CIBIL score does not guarantee personal-loan approval.
Lenders may also assess your:
Income
Your income helps determine whether you can comfortably repay the proposed EMI.
Employment Stability
A stable employment history may strengthen your application.
Existing EMIs
If a significant portion of your monthly income already goes toward debt payments, a lender may reduce the loan amount it is willing to offer.
Debt-to-Income Position
Lenders may examine your existing financial obligations compared with your income.
Age
Age can affect eligibility and maximum loan tenure depending on the lender’s policies.
Employer or Business Profile
For salaried applicants, some lenders may consider the employer’s profile. Self-employed applicants may be evaluated based on business income, financial documents and business stability.
Example: How CIBIL Score Can Affect a Personal Loan
Consider two hypothetical applicants:
Applicant A
- CIBIL score: 780
- Stable employment
- Regular income
- Low existing debt
- Timely repayments
Applicant B
- CIBIL score: 640
- Irregular repayment history
- High existing debt
- Several recent credit applications
Even if both applicants request the same ₹5 lakh personal loan, their applications may be assessed differently.
Applicant A’s stronger credit history may provide access to more favorable terms, while Applicant B may face stricter eligibility conditions.
This example illustrates why lenders generally consider the entire credit profile rather than the CIBIL score alone.
Should You Take a Personal Loan Just Because You Have a High CIBIL Score?
No.
A high CIBIL score can make borrowing easier, but it does not mean taking a loan is automatically the right financial decision.
Before borrowing, consider:
- Why you need the loan
- Total interest payable
- Processing fees
- EMI affordability
- Existing debts
- Prepayment or foreclosure charges, if applicable
- Whether the expense can be postponed or funded from savings
A loan should fit comfortably within your budget.
Tips Before Applying for a Personal Loan
Follow these steps before submitting an application:
Step 1: Check your CIBIL score and credit report.
Step 2: Review your existing loans and EMIs.
Step 3: Calculate how much EMI you can realistically afford.
Step 4: Compare interest rates and fees from different lenders.
Step 5: Check the lender’s eligibility requirements.
Step 6: Avoid unnecessary loan applications.
Step 7: Keep income and employment documents ready.
Step 8: Read the loan agreement carefully before accepting the offer.
Frequently Asked Questions
Is 750 a good CIBIL score for a personal loan?
Yes. A score of 750 or above is generally considered strong and may improve your chances of receiving favorable loan terms, subject to the lender’s other eligibility criteria.
Is 700 enough for a personal loan?
A 700 score can be sufficient with some lenders. However, approval and loan terms depend on income, existing debt, repayment history and the lender’s policies.
Can I get a personal loan with a 600 CIBIL score?
It may be possible with some lenders, but approval can be more difficult and the terms may be less favorable.
What is the ideal CIBIL score for a personal loan?
There is no officially guaranteed “ideal” score. In general, a score of 750 or higher is considered a strong position for many credit applications.
Does salary matter more than CIBIL score?
Both can matter. A high income does not automatically compensate for a poor credit history, while an excellent credit score does not guarantee approval if income or repayment capacity is insufficient.
How can I increase my CIBIL score quickly?
There is no guaranteed instant method. Paying EMIs and credit-card bills on time, reducing high credit utilization, limiting unnecessary applications and correcting errors in your credit report can help build a healthier credit profile over time.
Final Thoughts
A CIBIL score of 750 or above is generally considered a strong score for a personal loan, but there is no universal score that guarantees approval.
A lender may look at your complete financial profile, including income, employment stability, existing EMIs, credit history and recent credit applications.
If your score is around 700, you may still qualify for a personal loan depending on the lender. If your score is below 650, improving your credit profile before applying may be worth considering.
Ultimately, the goal should not simply be to achieve a particular number. Maintaining consistent repayments, manageable debt and responsible credit usage can help create a stronger financial profile and potentially improve your access to credit when you genuinely need it.