Ask ten people in India how they budget and you will get ten different answers — and most of them will be some version of “I don’t really budget, I just try not to spend too much.” Then the month ends, the salary is gone, and nobody can quite say where it went. The rent is paid, the groceries are bought, a few UPI payments happened somewhere in between, and the savings account looks exactly the way it did on the first of the month.
That is not a discipline problem. It is a system problem. Budgeting fails in India not because people are careless, but because most budgeting advice was written for someone else — someone with a predictable salary, no family obligations, and no festival season. A monthly budget in India has to survive school fees, a parent’s medicine bill, a cousin’s wedding, and Diwali. The 50/30/20 rule is one of the few methods simple enough to survive all of that, and this guide shows how to make it work with a real Indian salary.
What the 50/30/20 rule actually means
The rule is simple on the surface. Split your take-home pay — the money that actually lands in your bank account after tax, EPF and other deductions — into three buckets.
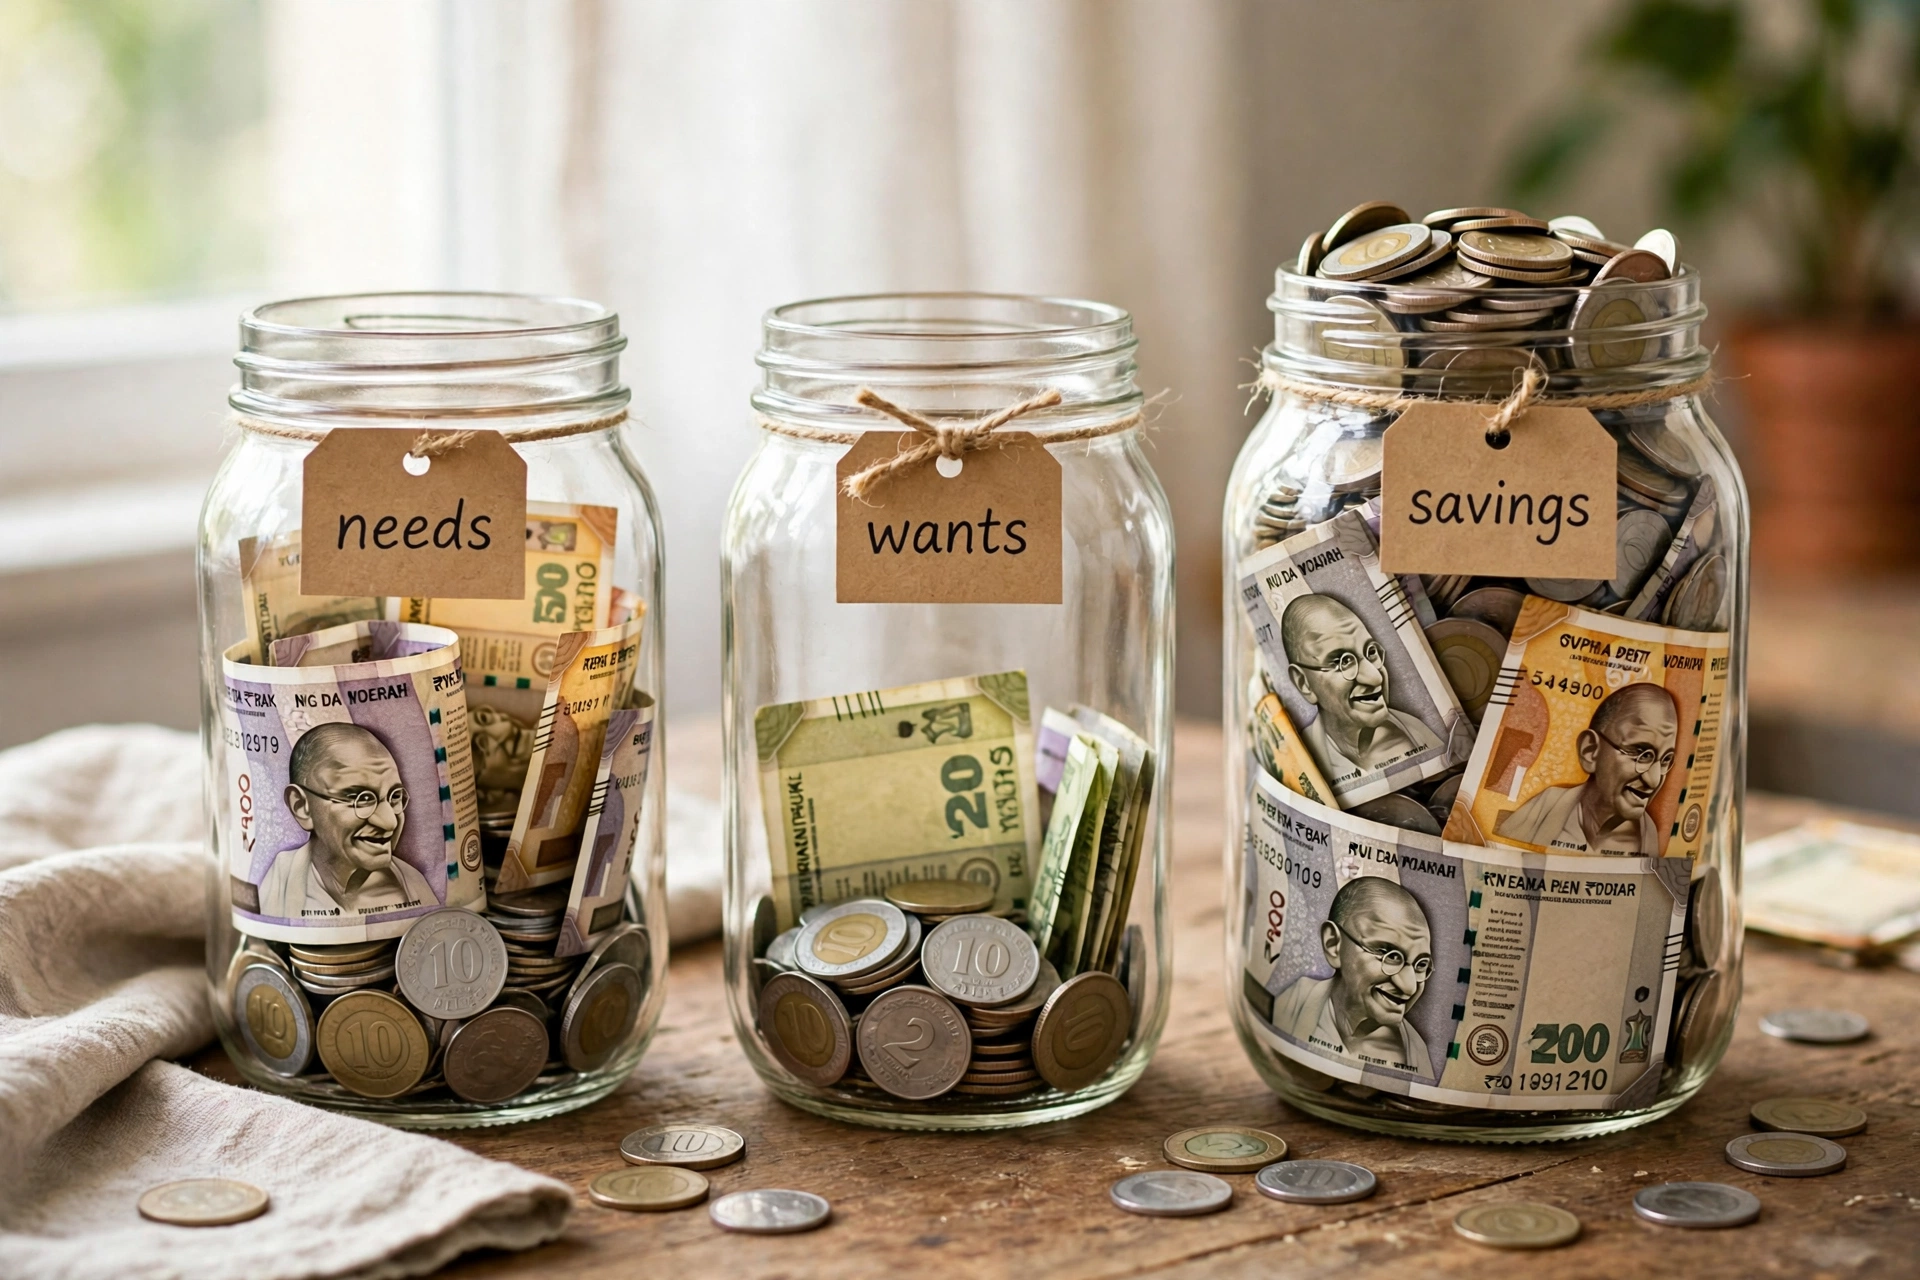
Fifty percent goes to needs. These are the things you cannot skip: rent or home loan EMI, groceries, electricity and water bills, transport to work, school fees, basic medicines, and your phone recharge. If you do not pay them, life stops working.
Thirty percent goes to wants. These are the things that make life enjoyable but are not strictly necessary: eating out, a streaming subscription, a new pair of shoes, a weekend trip, ordering in instead of cooking. You can live without them, but a life with none of them is not a life most people want to live.
Twenty percent goes to savings and debt repayment. This is your emergency fund, your SIP, your PPF, your extra EMI payments, and anything that builds your future. The rule treats this as a fixed bill, not as whatever happens to be left over — because whatever is left over is usually nothing.
Take a concrete example. Say your in-hand salary is ₹60,000 a month. The rule gives you ₹30,000 for needs, ₹18,000 for wants, and ₹12,000 for savings. On ₹40,000 in hand, it is ₹20,000, ₹12,000 and ₹8,000. On ₹1,00,000, it is ₹50,000, ₹30,000 and ₹20,000. The percentages stay the same; the rupees change with your income.
The beauty of the rule is that it is a starting point, not a law. If your rent alone eats 40% of your salary — common in Mumbai or Bengaluru — your numbers will not look like the textbook. That does not mean the rule has failed. It means you need to see the gap clearly and adjust deliberately, which is exactly what a budget is for.
Step one: find your real in-hand income
Most budgets go wrong in the first five minutes, because people budget on their CTC instead of their take-home pay. A CTC of ₹9 lakh a year sounds like ₹75,000 a month. After income tax, EPF, professional tax and any insurance premium your employer deducts, the amount that actually arrives might be ₹58,000. Budgeting on ₹75,000 means planning to spend money that never reaches you.
So start with the number in your bank statement. If your salary varies — you are a freelancer, you earn incentives, or you run a small business — use the average of the last three months, and budget on the lowest of the three. A freelancer who earns ₹80,000 one month and ₹45,000 the next should budget on ₹45,000 and treat the good months as a bonus, not as the baseline.
Also count any regular side income, but only if it is genuinely regular. A fixed ₹5,000 a month from a weekend tuition job counts. An occasional ₹10,000 from selling something on OLX does not. Irregular income belongs in savings, not in the monthly plan.
Step two: sort your spending honestly
Now comes the part most people avoid: writing down where the money actually goes. Not where you think it goes. Where it goes.
The easiest way to do this in India today is to open your bank statement and your UPI history for the last month and sort every transaction into the three buckets. Do it for one month properly, and you will learn more about your money than a year of guessing. Almost everyone finds a surprise. It is usually food delivery, or the small daily UPI payments — ₹120 here, ₹250 there — that add up to ₹6,000 or ₹7,000 a month without anyone noticing.
Here is how to sort the tricky ones.
Rent, home loan EMI, groceries, vegetables, cooking gas, electricity, water, internet, commuting, school fees, and regular medicines are needs. So is the minimum payment on a loan — the EMI itself is a commitment, even though the loan was a choice when you took it.
Eating out, food delivery beyond the occasional treat, streaming subscriptions, gym memberships, new clothes beyond replacement, gadgets, holidays, and gifts are wants. Be honest here. A ₹1,000 dinner every Friday is a want, even if it feels like a need by Friday evening.
SIP, RD, PPF, EPF top-up, emergency fund contributions, and extra payments above the minimum EMI are savings. Paying off a credit card in full is savings in reverse — it protects your future money — so the part of a credit card payment that clears a past balance belongs here too, while the part that pays for this month’s spending belongs with the spending itself.
One category deserves a special mention: family support. If you send ₹5,000 a month to your parents, that is a need in the real sense — it is not optional for you. Put it in needs and adjust the other buckets around it. A budget that pretends a fixed family obligation does not exist is a budget that will be abandoned by the second week.
Step three: make the numbers fit your real life
Now compare your actual split with 50/30/20. Most Indian households will find needs running higher than 50%, often 60% or even 65%. That is normal, and it is not a reason to give up.
If needs are at 60%, start with 60/25/15 and work towards 50/30/20 over a few months. A budget that demands a sudden cut from 65% to 50% in one month will fail, and a failed budget teaches you nothing except that budgeting does not work. A budget that moves from 65% to 60% this month and 55% next quarter is a budget that is actually changing your life.
The fastest way to bring needs down is usually the biggest line item: housing. A family paying ₹18,000 rent on a ₹60,000 salary is spending 30% on rent alone. Moving to a slightly smaller place, or a neighbourhood one metro stop further out, can free up ₹3,000 to ₹4,000 a month — more than any amount of skipping coffee will ever save. The second-biggest lever is usually transport: a two-wheeler EMI plus petrol often costs more than people realise, and the metro or a bus pass can be a genuine saving.
Wants are the easiest bucket to trim without pain, because they are the most flexible. You do not need to cut all of them. Cut the ones you do not remember enjoying. The food delivery order you placed because you were too tired to cook is a different thing from the dinner with friends you looked forward to all week. Keep the second one. Question the first one.
And savings — the 20% — should be automated. The day your salary arrives, an auto-debit should move your savings amount into a separate account or a SIP before you have a chance to spend it. If you wait until the end of the month to save what is left, the answer will almost always be that nothing is left. Pay yourself first is not a slogan; it is the only mechanism that has ever reliably worked.
A worked example: ₹50,000 in hand
Let us make this concrete with a salary many Indians will recognise: ₹50,000 a month in hand, living in a mid-sized city, single or newly married, renting a one-bedroom flat.
Needs at 50% is ₹25,000. In practice it might look like this: rent ₹10,000, groceries and vegetables ₹6,000, electricity and water ₹1,500, cooking gas ₹1,100, transport ₹2,000, phone and internet ₹1,000, medicines and toiletries ₹1,500, and a small buffer of ₹1,900 for the things you forgot. That is ₹25,000, and it is tight but honest.
Wants at 30% is ₹15,000. This could be eating out twice a week at ₹500 a time (₹4,000), a streaming subscription and a music app (₹800), a weekend outing or movie (₹2,000), clothes and personal items (₹2,000), gifts and festivals averaged out (₹2,000), and a little extra (₹4,200) for whatever comes up. The point is not to spend exactly ₹15,000 — it is to know that the ceiling exists.
Savings at 20% is ₹10,000. Split it sensibly: ₹5,000 into a SIP in a diversified mutual fund, ₹3,000 into an RD or a savings account earmarked as an emergency fund, and ₹2,000 into a PPF or an ELSS for tax saving. In a year, that is ₹1,20,000 saved — and because the SIP and the emergency fund grow separately, you can see the progress.
Now change the numbers and the same structure still works. On ₹30,000 in hand, needs might be ₹18,000, wants ₹6,000, savings ₹6,000. On ₹1,20,000 in hand, needs might be ₹50,000, wants ₹35,000, savings ₹35,000. The percentages are a guide; the habit of splitting first and spending second is the real lesson.
Where Indian budgets usually break
A budget is not a spreadsheet. It is a promise you make to yourself, and Indian life tests that promise in specific ways. Knowing the weak points in advance helps.
Festivals are the first. Diwali, weddings, Rakhi, a child’s birthday — the spending spikes are real and they are not optional in the social sense. The fix is to budget for them monthly. If you spend roughly ₹30,000 a year on festivals and family occasions, set aside ₹2,500 a month in a separate savings account. When Diwali arrives, the money is already there, and the budget does not collapse.
Medical expenses are the second. A single hospital visit can wipe out two months of savings. This is why the emergency fund matters more than any investment, and why a basic health insurance policy — even a modest ₹5 lakh family floater — belongs in the needs bucket, not as an afterthought. Budgeting without insurance is planning that assumes nothing will ever go wrong.
The third is the salary itself. Annual increments, bonuses, and festival advances feel like free money. They are not. Decide in advance what a bonus is for: half to savings, half to something you enjoy, for instance. If you do not decide, the bonus will quietly become a new phone and a few dinners out, and by January it will be gone.
And the fourth is the most common of all: the budget that is too strict. A plan that allows zero spending on wants will last about ten days. The 30% exists for a reason — it is what makes the other 70% sustainable. A budget you actually follow at 80% accuracy for a year beats a perfect budget you abandon in a fortnight.
The simplest way to track it
You do not need a complicated app. A notebook, a spreadsheet, or the notes app on your phone is enough. The method that works for most people is the envelope method in digital form: three bank accounts, or one account with three sub-accounts if your bank supports them. Salary arrives in the main account. On payday, the savings amount moves out automatically. What remains is split between needs and wants, and the wants money sits in a separate account or a wallet with a visible balance.
If you prefer an app, there are several Indian budgeting apps that read your SMS and categorise spending automatically. They are useful for the first month, when you are discovering where the money goes. After that, most people find a simple weekly check is enough: every Sunday, five minutes, look at what you spent, compare it with the plan, and adjust the coming week. The weekly check is what turns a budget from a one-time exercise into a habit.
A monthly review matters too. At the end of each month, ask three questions. Did my needs stay within their share? Did I enjoy the money I spent on wants, or did most of it vanish on things I cannot remember? Did my savings actually move? If the answers are mostly yes, the budget is working — even if the percentages are not exactly 50/30/20 yet. If the answers are no, change one thing next month, not everything. One change at a time is how budgets survive.
Starting today, not next month
The most common reason budgets fail is that people wait for the right month to start — next month, after the wedding, once the increment comes. There is never a right month. Start with the money that is in your account right now.
Today, write down your in-hand income. Tonight, spend twenty minutes sorting last month’s spending into needs, wants and savings. Tomorrow, when the salary lands, move the savings amount out first — even if it is only ₹2,000 to begin with. Then live the month with the other two buckets visible, and check in every Sunday.
You do not need to be perfect. You need to be honest about the numbers and consistent about the habit. A monthly budget is not about spending less on everything. It is about deciding, before the month begins, what your money is for — and then making sure that at the end of the month, your savings account can prove you meant it.