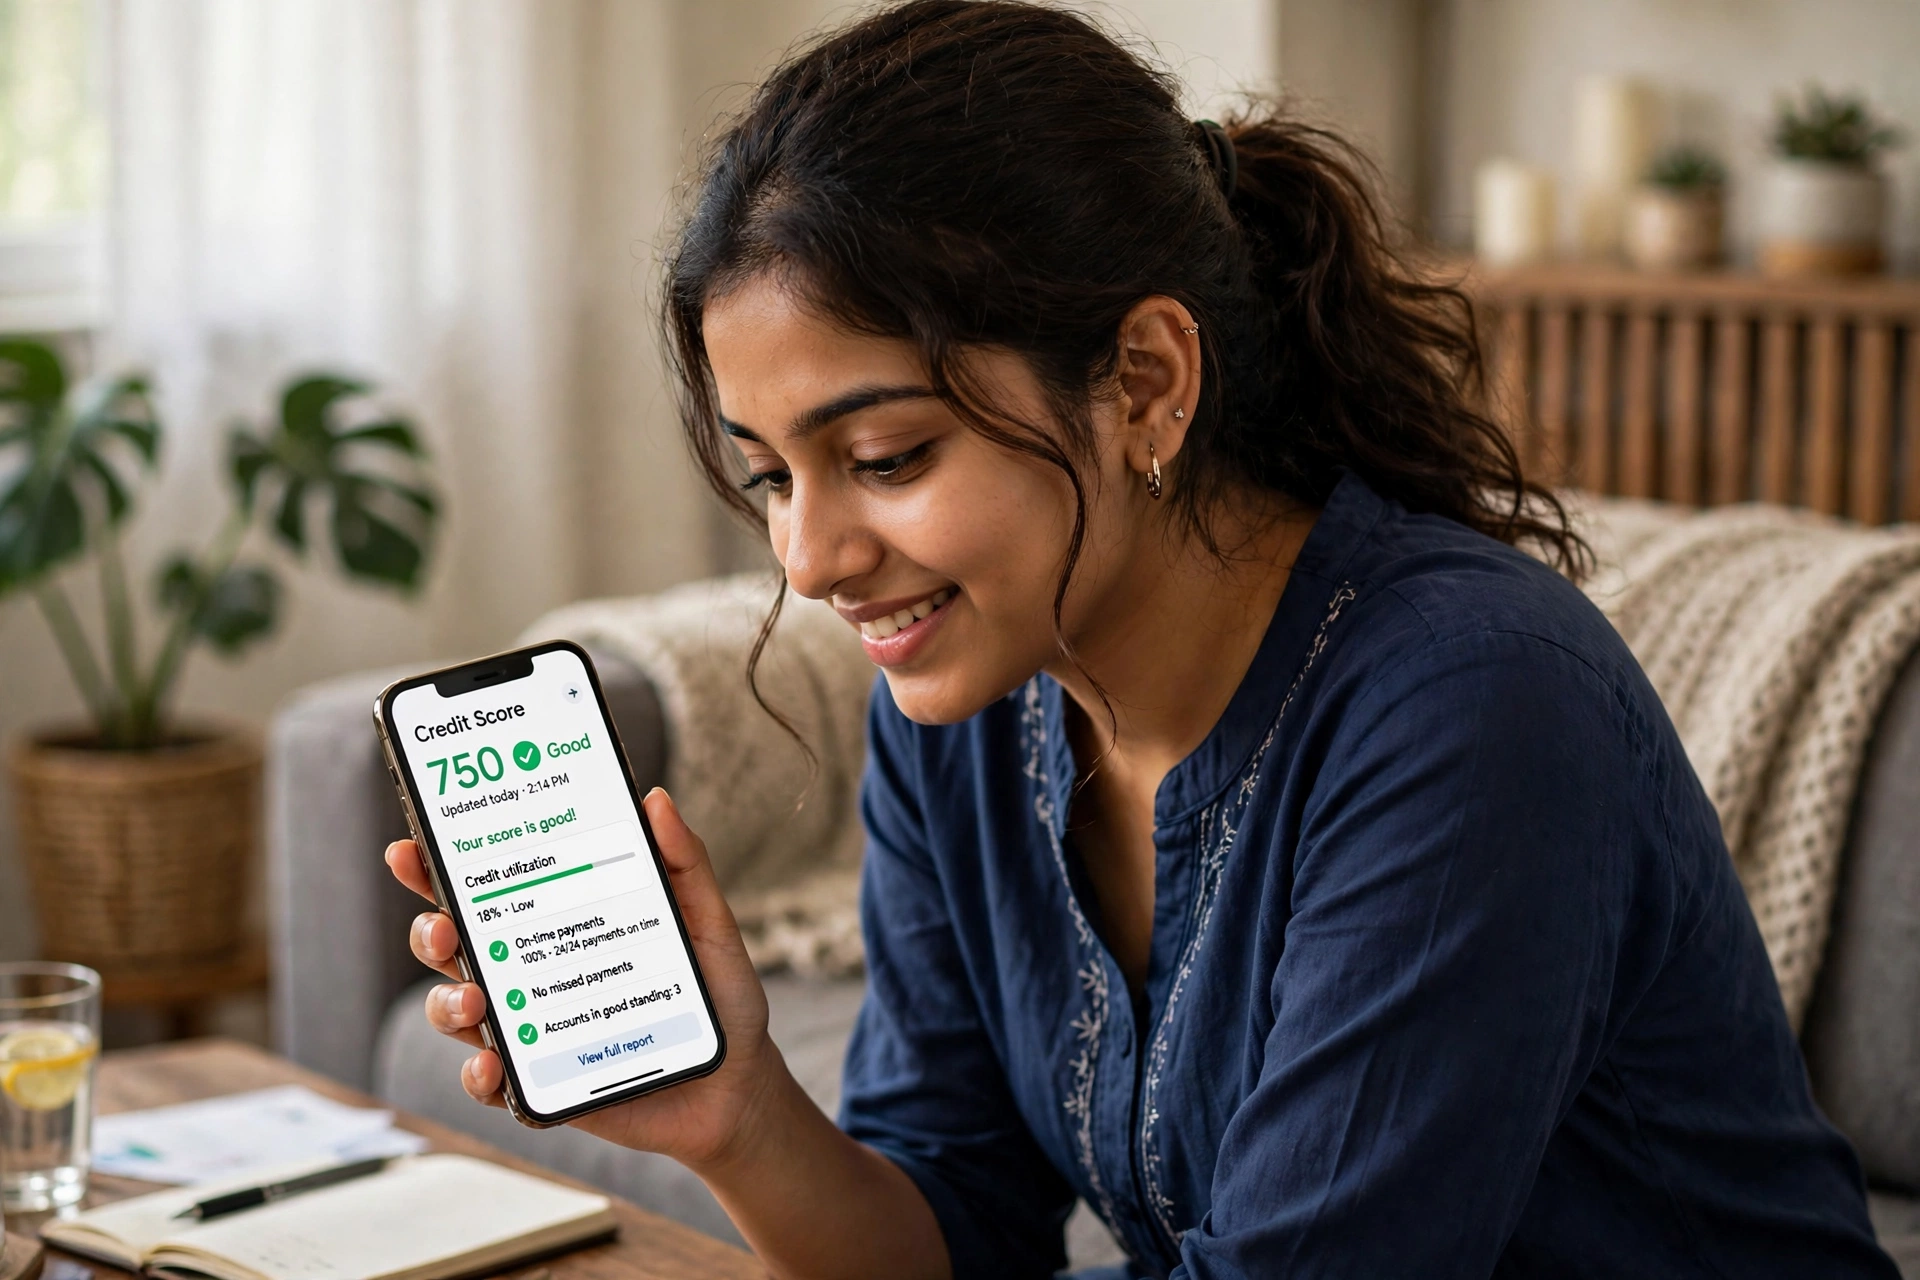
Most Indians first hear about their credit score when a loan gets rejected, or when a bank offers a higher interest rate than a friend got for the same loan. By then, the score has already done its work quietly in the background. It is worth understanding it before you need it, because building a good score takes months, while damaging one can happen in a single missed payment.
Your credit score in India is a three-digit number, usually between 300 and 900, that sums up how reliably you have repaid borrowed money. The best-known score comes from CIBIL, now called TransUnion CIBIL, but other bureaus like Experian, Equifax and CRIF High Mark also maintain scores. Banks check one or more of these before approving a loan or credit card. A score of 750 or above is generally considered good. Below 650, approvals get harder and interest rates get higher.
The score is not a judgement of how rich you are. A person earning ₹2 lakh a month with missed EMIs can have a lower score than someone earning ₹50,000 who pays every bill on time. It measures behaviour, not income.
How your score is actually calculated
Payment history carries the most weight. Every EMI and credit card payment is reported to the bureaus each month. Paying on time, every time, builds the score steadily. A single payment delayed by more than 30 days can leave a mark, and a 90-day delay hurts much more.
Credit utilisation is the next big factor. This is how much of your available credit you actually use. If your card limit is ₹1 lakh and you regularly spend ₹90,000 on it, lenders see heavy dependence on credit, even if you pay the full amount later. Keeping utilisation below 30% of your limit is a widely used rule of thumb, and below 20% is better still.
Length of credit history matters too. A credit card you have held and used responsibly for five years tells a lender more than a new card opened last month. That is one reason closing your oldest card can sometimes lower your score, even though it feels like tidying up.
The mix of credit also counts. A healthy mix — say, a home loan or personal loan repaid steadily alongside a credit card — looks better than only one type of borrowing. This does not mean you should take a loan just to improve your mix. It simply means that different kinds of responsible borrowing, over time, strengthen the picture.
Finally, every fresh loan or card application triggers a hard enquiry, a formal check by the lender. One or two enquiries are normal. Six applications in a month look desperate to a lender, and can shave points off your score.
Why a low score costs real money
The difference is not abstract. Two people applying for the same ₹10 lakh personal loan might be offered very different rates. The borrower with a score above 780 might get 11%, while someone at 680 might be offered 14% or more, if approved at all. Over three years, that rate gap costs tens of thousands of rupees in extra interest.
A low score can also mean a smaller approved amount, a demand for a co-applicant or collateral, or a straight rejection. Home loans are usually more forgiving than unsecured personal loans, because the property itself is security, but even there a weak score can push the rate up or delay approval.
It works the other way too. A strong score gives you negotiating power. Banks compete harder for borrowers who look safe, and you can ask for a lower rate, a fee waiver, or a higher card limit with a better chance of hearing yes.
If you have no credit history at all
Many young earners and first-time borrowers have no score, or a score of zero, because they have never borrowed. That is not a bad score, but it is also not a helpful one. Lenders have nothing to judge.
The simplest starting point is a secured credit card, issued against a fixed deposit. You might put ₹25,000 in an FD and get a card with a similar limit. Use it for small, regular expenses — groceries, a mobile recharge, a fuel bill — and pay the full amount before the due date every month. Within six to twelve months, you will have a real repayment record, and your score will start to take shape.
A small consumer loan or a credit card taken alongside a salary account can serve the same purpose, but only if you are sure you can repay on time. The goal at this stage is not to borrow more. It is to create a clean, boring record of paying on time.
The habits that actually improve a score
Pay on time, without exception. Set up auto-debit for at least the minimum amount on every card and EMI, so a forgotten due date never becomes a missed payment. Then pay the full card balance whenever you can, because paying only the minimum keeps interest compounding and utilisation high. If you are unsure why minimum payments are so costly, our explainer on the credit card minimum due trap in India works through the maths.
Keep utilisation low. If your limit is ₹50,000 and you need to spend ₹40,000 in a month, consider paying part of the bill mid-month, before the statement is generated. The bureau often sees the statement balance, so a mid-month payment can lower the utilisation that gets reported.
Do not apply for several cards or loans at once. Space applications out, and apply only when you genuinely need the product. If a bank rejects you, find out why before applying elsewhere the same week, or you will collect hard enquiries for no benefit.
Check your report once or twice a year. Mistakes happen — a loan you closed years ago may still show as open, or a payment you made may be marked late. You can raise a dispute with the bureau for free, and getting an error corrected can lift your score. Use the official bureau website or a bank-partnered service, and be wary of apps that promise to raise your score for a fee. No one can legally delete a genuine missed payment from your record.
Keep old accounts open if they cost you nothing. That long-held card with no annual fee helps your average credit age. If a card charges a high annual fee and you never use it, closing it may still be sensible, but weigh the fee against the effect on your history first.
What to do if your score is already low
First, do not panic, and do not take a new high-interest loan to “fix” the score. Start by clearing any overdue amounts, starting with the oldest or the most heavily penalised. Even one account brought current stops further damage from that account.
Next, build a fresh run of on-time payments. Scores recover gradually, and lenders look at recent behaviour more kindly than a single old slip. Six months of clean payments usually shows a visible improvement, and twelve months can change the picture substantially.
If you are carrying multiple debts, focus on the structure, not just the score. Paying off the highest-interest debt first saves the most money, while clearing the smallest balance first can give you momentum. Either approach beats paying only minimums everywhere. Our step-by-step guide on getting out of debt in India lays out a practical order for tackling several debts at once.
Avoid settlement if you can repay in full. A loan marked “settled” — meaning the lender accepted less than the full amount — stays on your report and looks worse than a loan marked “closed” after full repayment. Settlement is sometimes unavoidable in genuine hardship, but it is not a shortcut to a good score.
How long does improvement actually take?
This is the question everyone asks, and the honest answer is that it depends on what damaged the score. A high utilisation problem can improve within one or two billing cycles, because the next reported statement shows a lower balance. A single late payment fades in impact over six to twelve months, provided nothing else goes wrong in between. A settled loan or a written-off account can weigh on the report for years, though its influence lessens with time.
That timeline is why starting early matters so much. If you plan to apply for a home loan in 2027, the payments you make in late 2026 are the ones that will shape that application. Waiting until the month before you apply leaves no time for a record to form. Lenders also look at the trend, not just the number on the day. A score rising steadily from 680 to 740 over a year tells a better story than a score that jumped once and then stalled.
It also helps to keep your financial life simple while you rebuild. One or two cards used carefully are easier to manage than five cards with different due dates, different limits and different reward schemes. Consolidate where you can, set reminders a few days before each due date rather than on the day itself, and keep a small buffer in your account so an EMI auto-debit never bounces for lack of funds. A bounced EMI can be reported just like a missed one, and it can also attract bank charges on top.
If you are a couple planning a joint home loan, remember that both scores are usually checked. One strong score does not fully cover a weak one. It is worth both partners checking their reports and fixing errors well before you start house-hunting, rather than discovering a problem when a builder is waiting for a booking amount.
Myths worth dropping
Your score does not improve because you earn more, keep a large bank balance, or pay your rent on time, unless that rent is reported through a specific product. It improves because you borrow and repay reliably.
Checking your own score does not lower it. A self-check is a soft enquiry and has no effect. Only lender checks, the hard enquiries, count, and even those fade in importance over time.
Finally, there is no quick fix. Anyone promising to raise your score from 620 to 800 in a month is selling hope, not a service. Real improvement is slow because trust is slow. That is actually the point of the system. A score built over years of steady payments tells a lender something a one-month trick never could.
A good credit score will not make you rich, and a bad one does not make you a bad person. It is simply a record, and like most records, it responds to steady, unglamorous habits: pay on time, borrow less than you can afford, check for errors, and give it time. Start before you need a big loan, and when the day comes to apply for a home loan or a car loan, your past self will have already done the negotiating for you.