Most couples in India do not fight about love. They fight about money — quietly, repeatedly, and often over small things. A ₹400 food delivery order. A pair of shoes bought without discussion. A transfer to a parent that one partner knew about and the other did not. No single amount breaks a household. What breaks trust is the feeling that money decisions are happening separately while the bills are shared.
Couples money management in India is not about one person controlling the budget or both partners tracking every rupee with suspicion. It is about building a simple joint plan that both people understand, agree to, and can actually follow in a normal month. When that plan exists, money stops being a weekly argument and starts being a shared project — covering joint budgeting, shared goals, separate spending money, and honest money talks.
Why Money Becomes Sensitive After Marriage
Before marriage, most people manage money alone. You earn, you spend, you save what is left, and nobody questions your choices unless your balance runs out. After marriage, that changes overnight. Rent, groceries, electricity bills, EMIs, insurance premiums, and festival expenses suddenly belong to two people, even if only one person pays them in a given month.
Many couples never discuss this shift. One partner pays the rent, the other handles groceries and UPI payments, and both hope the maths works out. Then a big expense arrives — a medical bill, a family wedding, a car repair — and the gaps show up all at once. There is another layer specific to India: parents may need support, siblings may need help, and festival gifts are often non-negotiable in practice even if they are not in any budget.
Start With a Money Date, Not a Money Fight
A money date is simply a fixed time, once a month, when both partners sit together and look at money without blame. Thirty to forty-five minutes is enough. Pick a relaxed time — a Sunday morning over chai, not in the middle of an argument about a purchase.
On the first money date, cover only four questions. What is coming in this month? What must go out no matter what? What do we want to save? What can each of us spend freely? You do not need a spreadsheet with twenty categories. The point is honesty without fear: if one partner spent more on eating out than planned, that is information, not a crime. Write down what you agree, even as a short note on a phone, because memory is unreliable, especially about money.
Joint Account, Separate Accounts, or Both?
There is no single correct answer here, and couples waste a lot of energy searching for one. The system that works best for most Indian couples is a combination: one joint account for shared expenses and goals, plus individual accounts for personal spending.
Both salaries, or a fixed contribution from each salary, go into the joint account at the start of the month. Rent, utilities, groceries, EMIs, insurance, and SIPs are paid from that account. Each partner also keeps a personal account with a fixed amount of no-questions-asked spending money, for clothes, eating out with friends, hobbies, or gifts, without needing permission. Shared responsibilities are funded first, so essential bills are never left to chance, yet neither partner feels like a child asking for pocket money.
How much should personal money be? For many couples, ₹5,000 to ₹10,000 per person per month from a joint income of ₹80,000 to ₹1,20,000 feels workable. The exact number matters less than the principle: it is fixed, fairly agreed, and not raided when shared expenses run over. Keep transaction alerts on for both partners, so transparency is built into the system rather than demanded in arguments.
A Worked Example: A Joint Budget on ₹80,000 a Month
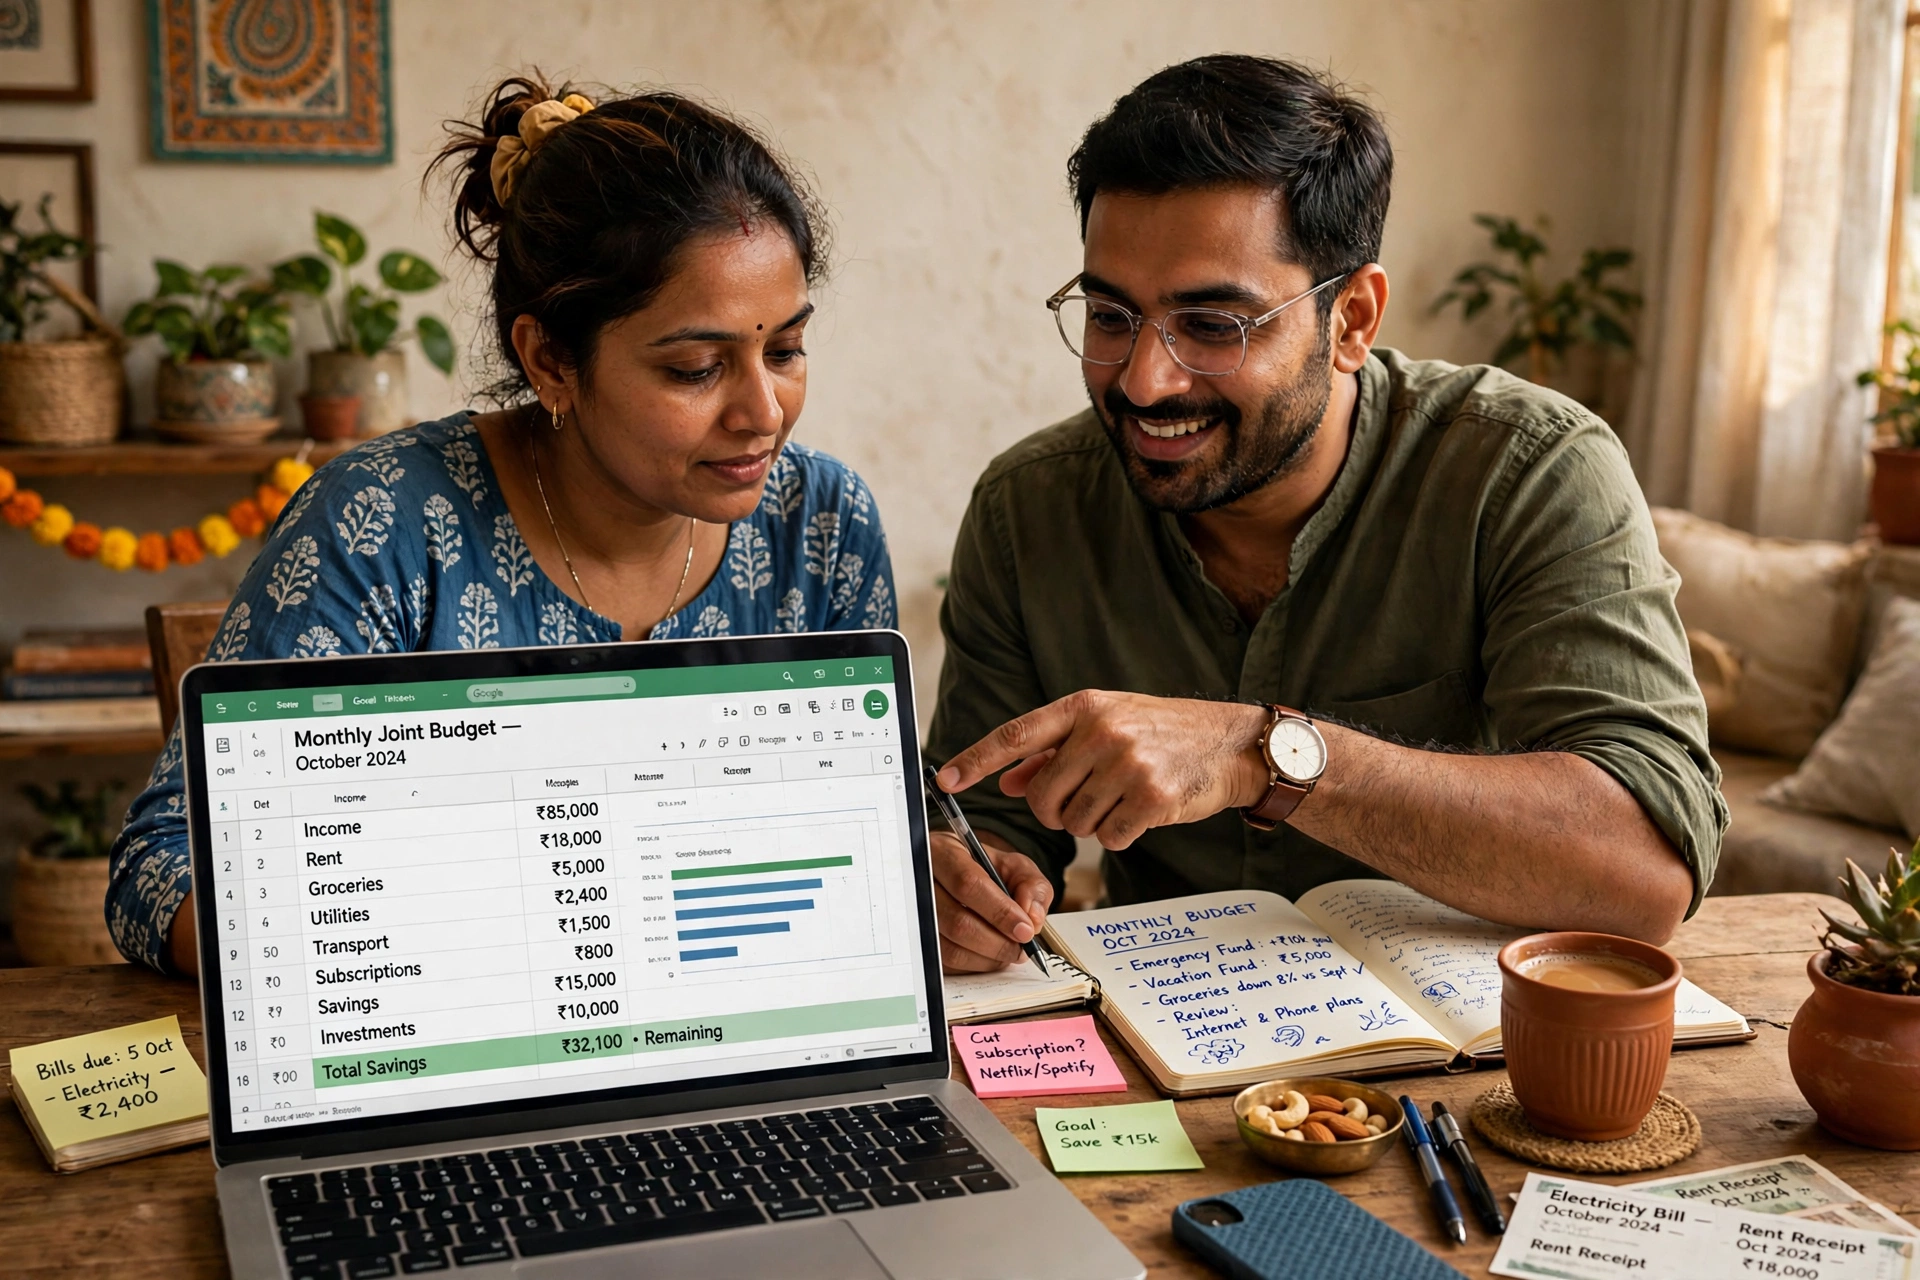
Take a couple in a city like Pune or Bengaluru, with a combined take-home income of ₹80,000. Suppose rent is ₹22,000 for a two-bedroom flat, groceries and household supplies cost around ₹10,000, utilities and internet add up to ₹4,000, transport costs ₹5,000, health insurance averaged monthly is ₹2,000, and a small bike EMI is ₹6,000. That brings essentials to ₹49,000.
Next come the goals: ₹12,000 into SIPs, ₹5,000 into an emergency fund until it reaches a comfortable level, and ₹2,000 into a fund for festivals and family gifts — ₹19,000 in all. Each partner gets ₹5,000 as personal spending money, adding ₹10,000, and eating out together gets ₹2,000. The total is exactly ₹80,000. The point is not that every couple should copy these numbers. The point is that a joint plan forces choices to be visible: if this couple wants larger SIPs, they can see exactly what has to give.
A simple monthly joint budget
Essentials: Rent ₹22,000; Groceries and household ₹10,000; Utilities and internet ₹4,000; Transport ₹5,000; Insurance ₹2,000; EMI ₹6,000; Essentials total ₹49,000. Savings and goals: SIPs ₹12,000; Emergency fund ₹5,000; Festival and family fund ₹2,000; Savings total ₹19,000. Personal and fun: Partner A ₹5,000; Partner B ₹5,000; Eating out together ₹2,000; Personal and fun total ₹12,000. Grand total: ₹80,000.
Handling Different Spending Styles
Almost every couple has one saver and one spender, or at least one person who is more careful and one who is more relaxed about money. The careful partner is not automatically right, and the relaxed partner is not automatically careless. They often just have different relationships with money, shaped by how they grew up. Someone raised where money was tight may find it hard to spend even when the budget allows it. Someone raised with more comfort may not feel the same urgency about saving.
If a couple does not talk about these differences, they turn into labels — miser, spendthrift, irresponsible, controlling — and labels end conversations instead of solving problems. A better approach is to agree on guardrails rather than policing each purchase. For example, any single personal purchase above ₹10,000 gets a quick discussion first, not permission, just a discussion. Shared expenses above, say, ₹20,000 need both partners to agree before the money moves. Below those limits, personal money is personal, and shared money follows the budget. It also helps to separate the purchase from the person: instead of “You always waste money,” try, “That purchase was outside what we planned this month — how do we adjust?” The first starts a fight about character. The second starts a conversation about a number.
Shared Goals: Saving Together for Things You Both Want
Saving feels much easier when both partners can picture what the money is for. A vague goal like “we should save more” rarely survives contact with a sale on a shopping app. A specific goal — a home down payment in four years, a child’s education fund, a trip in 2028, or simply six months of expenses in an emergency fund — gives saving a reason to continue on boring months.
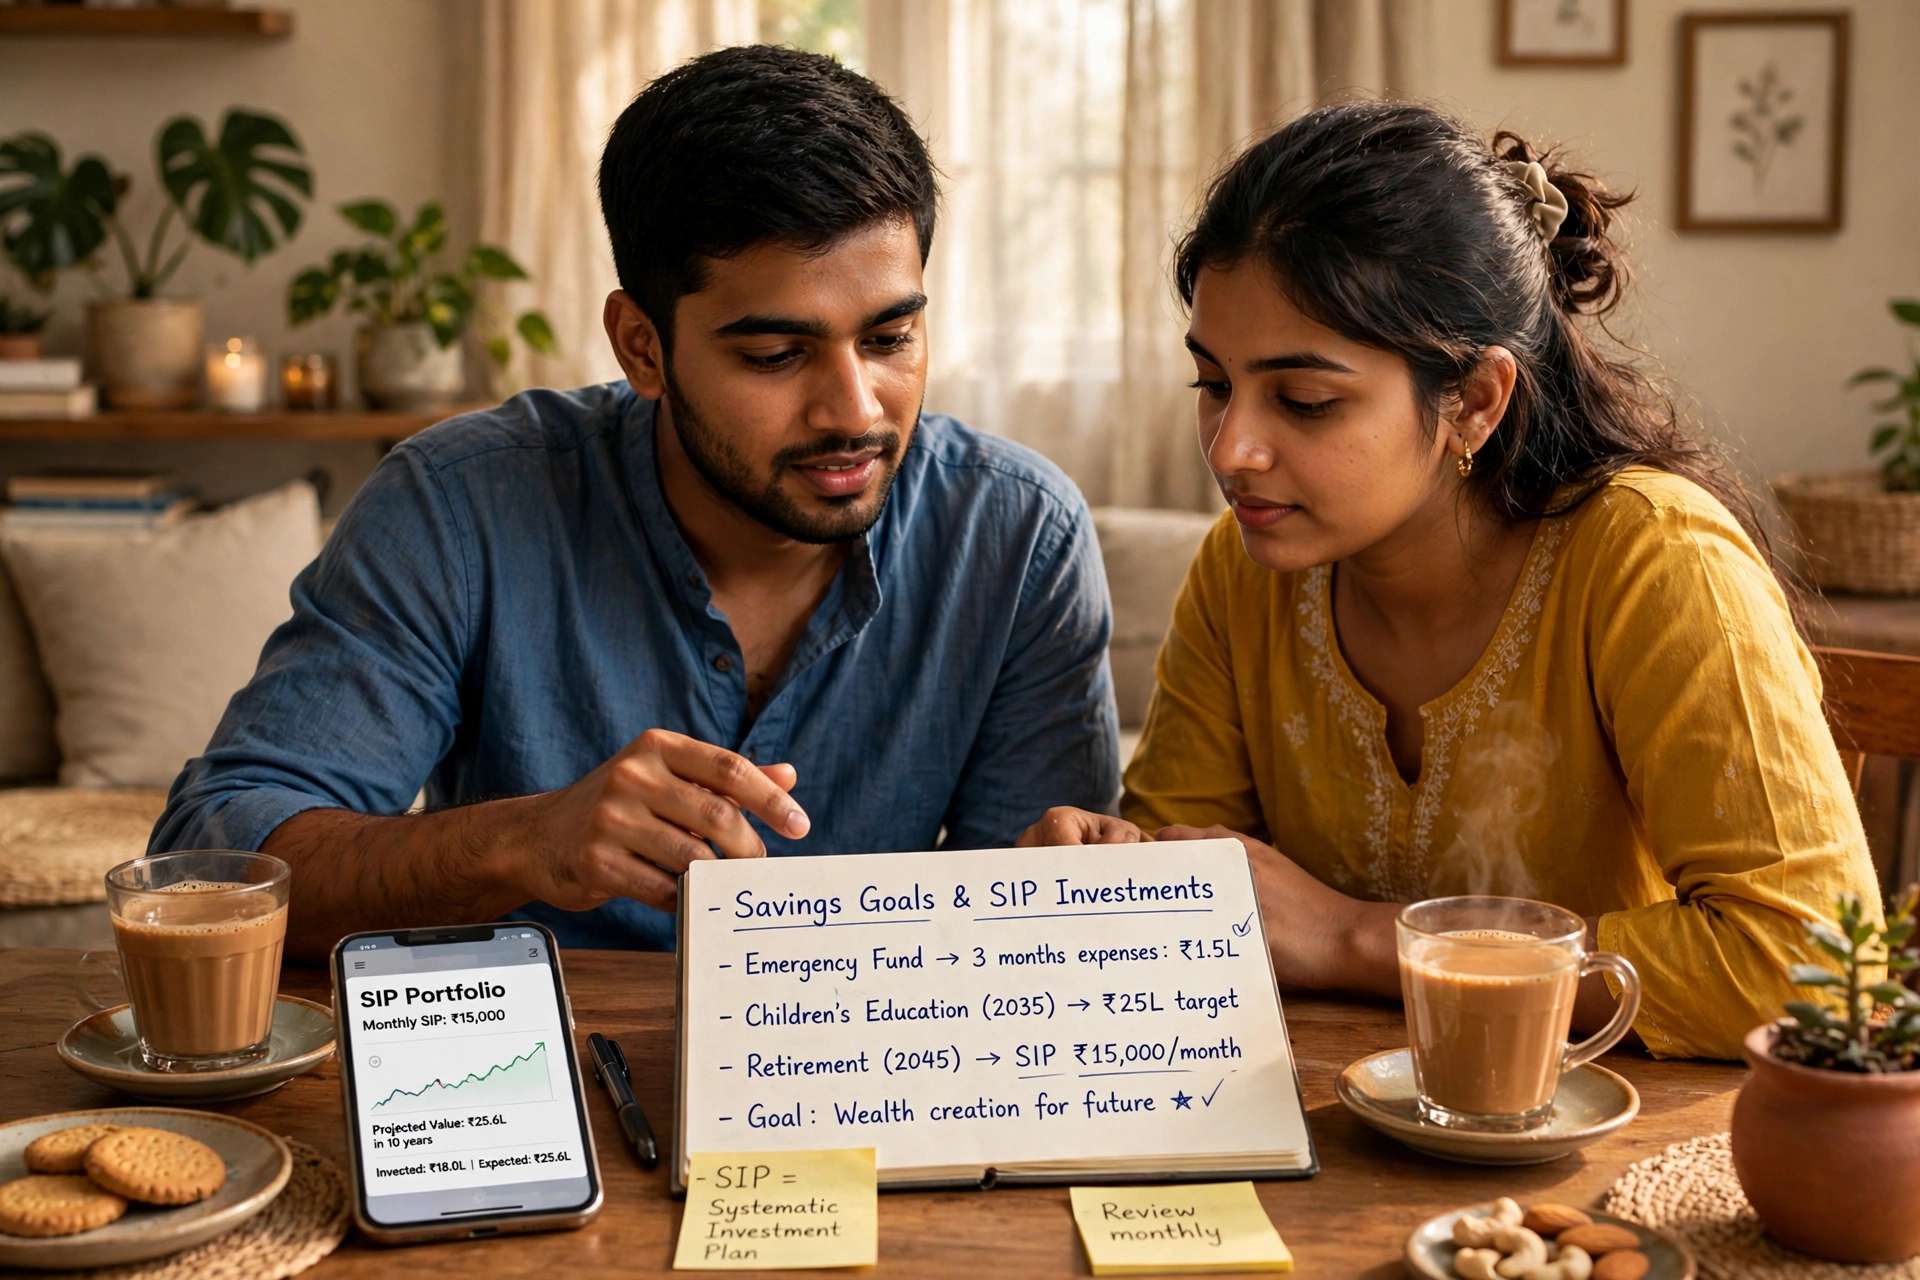
Start with the emergency fund, because it protects everything else. A good starting target is three to six months of essential expenses kept in a separate savings account or liquid fund, not mixed with daily spending money. If essentials cost ₹49,000 a month, that means roughly ₹1.5 lakh to ₹3 lakh over time. Built at ₹5,000 a month, it grows steadily, and it turns a job loss or medical emergency from a crisis into a manageable problem. You can read more about sizing it properly in this guide to building an emergency fund in India.
After the emergency fund is underway, list your shared goals together and rank them. A couple cannot fund everything at once — home, car, travel, retirement, and children’s education all compete for the same rupees. Maybe the home down payment comes first and the car waits two years. Automate the saving too: set SIPs and transfers to run in the first week of the month, right after salaries arrive.
Family Expenses and In-Laws: The Conversation Couples Avoid
This is often the hardest part of couples money management in India, and the part most generic budgeting advice ignores. Supporting parents, contributing to a sibling’s education, paying for family medical costs, or funding weddings are real expenses. Pretending they do not exist does not make them go away. It just makes them appear as surprise withdrawals that spark distrust.
The honest solution is to budget for family support openly, as a line item both partners can see. Many couples set aside a fixed family fund each month — say ₹3,000 to ₹5,000, depending on income — for parental support, gifts, and festival contributions. When a larger family expense comes up, it is discussed as a couple, with both partners weighing in, even if the money ultimately goes to one side of the family. Fairness does not always mean identical amounts: one set of parents may genuinely need more support at a given time. Fairness means both partners are informed, both are respected, and neither feels their family is always the one asked to wait.
One ground rule helps above all: no large family transfer happens in secret. Anything above the agreed fund gets a conversation first.
When One Partner Earns Much More Than the Other
Income gaps are common, and they can quietly distort a relationship if the couple lets earnings decide whose opinion counts. A partner earning ₹1,00,000 a month does not get more votes on household decisions than a partner earning ₹30,000, and a partner who manages the home full-time contributes real economic value even without a salary slip.
The joint-plus-personal system helps here, because contributions to the joint account can be proportional rather than equal. If one partner earns twice as much, they might contribute twice as much to shared expenses, while personal spending money stays equal. It is also worth agreeing in advance what happens if one partner stops working for a while — for childcare, study, health reasons, or a career break. Agreeing that the joint plan continues, and that personal money does not disappear for the partner not earning, prevents a painful renegotiation at an already stressful time.
Big Decisions: Home, Car, and Loans Together
Some money decisions are too large for one partner to make alone, and a home purchase is the biggest of them. Renting versus buying changes a couple’s finances for decades, affecting EMIs, savings, flexibility, and even where they can live and work. Before signing anything, compare the full costs honestly — not just EMI versus rent, but maintenance, registration, interest over the loan tenure, and the opportunity cost of a large down payment. A detailed comparison of rent versus buying a house in India can help frame that discussion with real numbers rather than family pressure or peer comparison.
The same principle applies to cars, personal loans, and credit cards. A car bought on a long loan may feel affordable month to month while quietly consuming the money meant for SIPs and the emergency fund. Large borrowing decisions deserve a joint conversation, a look at the total interest cost, and a clear repayment plan both partners accept. With credit cards, agree on who pays which bill and from which account — a bill paid late because each partner assumed the other handled it is a needless expense.
What to Do When You Disagree About Money
Disagreements will still happen, even with a good plan. The goal is not to eliminate them but to handle them without damage. Never discuss a major money decision when either partner is angry, tired, or hungry — postpone it to the next money date. Focus on the numbers and the options, not on past mistakes, and look for a compromise both partners can live with, rather than a win for one side. A plan one partner resents will be quietly sabotaged, whether by overspending, hiding purchases, or simply refusing to engage.
If disagreements keep repeating around the same topic, treat that as a sign the system needs changing, not the person. Adjusting the plan is not failure. It is exactly what a plan is for.
Building the Habit, Month by Month
Start small: in month one, hold the money date and agree on the joint account and personal money amounts. In month two, automate SIPs and bill payments. In month three, add the emergency fund target and the family fund. Review the plan every three to six months, or whenever income, rent, or family circumstances change — a new job, a baby, a move, or a parent’s retirement all change the numbers. Over time, money stops being a source of tension and becomes evidence of teamwork: the couple that once argued over a food delivery bill starts talking about how close they are to their home down payment, or how their SIPs have grown. That shift comes from deciding together, in advance, what money is for, and then trusting each other to follow the plan they built.