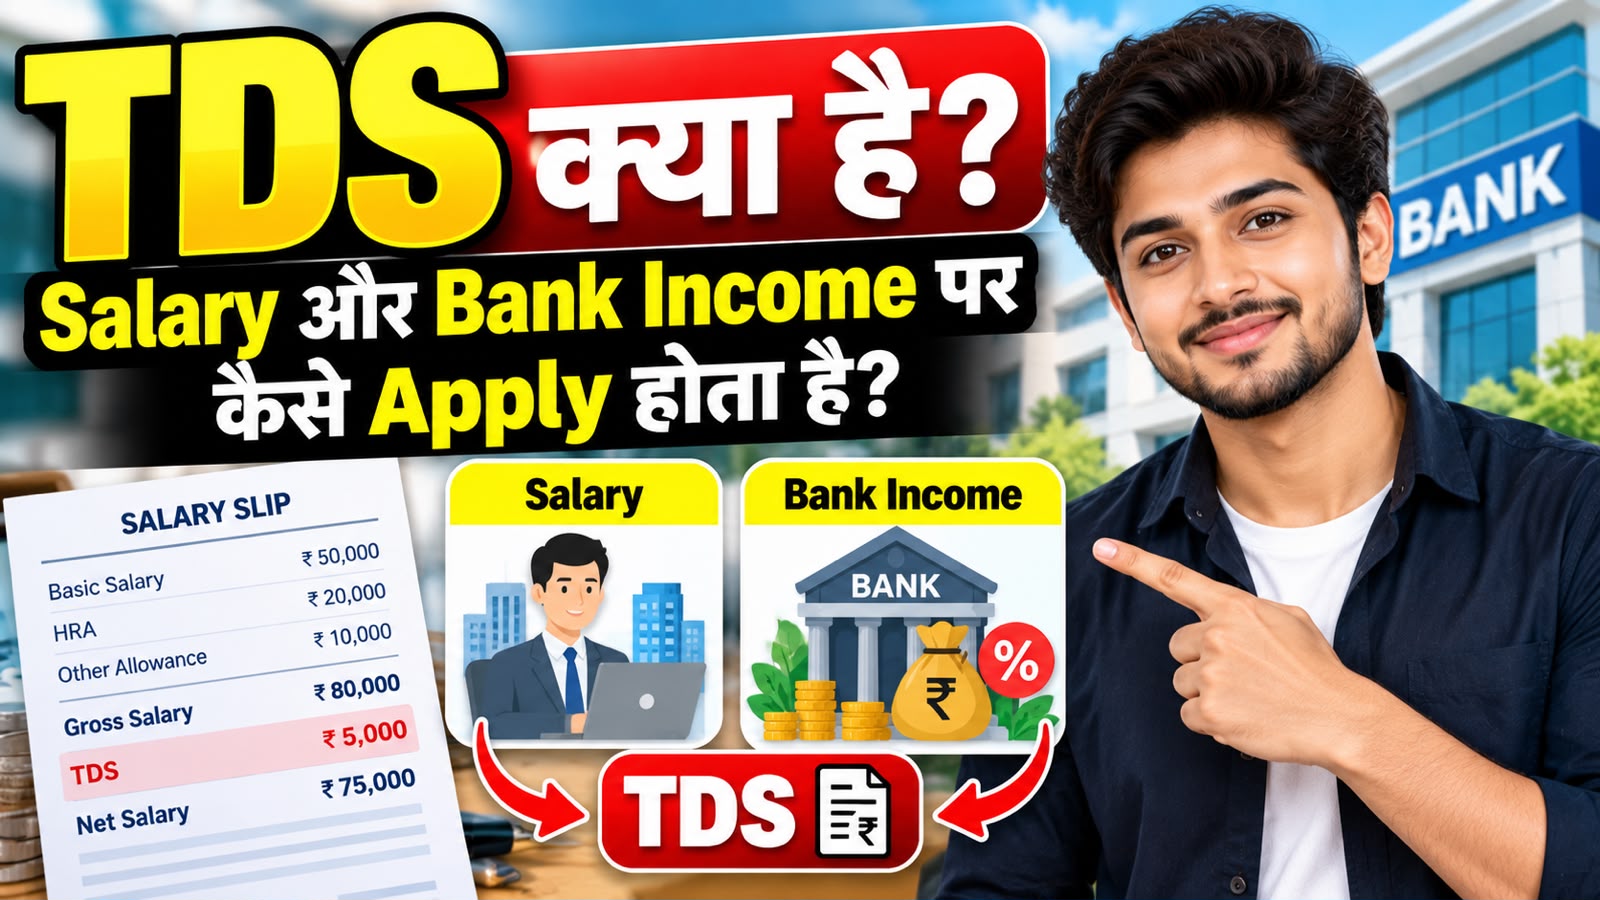
If you are working, have a Fixed Deposit (FD), or earn interest from your bank account, you may have heard about TDS. Sometimes, the salary you receive is slightly lower than expected because an amount has been deducted under TDS. Similarly, banks may also deduct TDS from certain types of interest income.
But what exactly is TDS? Why is it deducted? And if your employer or bank has already deducted TDS, do you have to pay tax again?
Let’s understand everything in simple language.
What Is TDS?
TDS stands for Tax Deducted at Source.
In simple words, TDS means that tax is deducted from certain payments before the money reaches you.
For example, suppose you receive a salary from your employer. If TDS is applicable to your income, your employer may deduct the required amount of tax before paying your salary. The deducted amount is then deposited with the government.
The same concept can apply to certain types of bank interest. For example, if you earn interest from an FD and the applicable conditions for TDS are met, the bank may deduct TDS from that interest.
The most important thing to remember is that TDS is not an additional tax. It is generally a part of your income tax that is collected in advance.
Why Is TDS Deducted?
You may wonder why tax is deducted before you actually receive the full payment.
The main reason is to make tax collection easier and more regular. Instead of collecting the entire tax amount at the end of the year, tax can be collected throughout the year whenever certain payments are made.
For example, suppose an employee has an estimated annual tax liability of ₹60,000. Depending on the applicable rules and calculation, the employer may deduct tax from the employee’s salary during the year.
This way, the employee does not necessarily have to arrange the entire tax amount at the end of the financial year.
How Does TDS Apply to Salary?
TDS on salary is quite common for salaried employees.
When you work for a company, your employer generally estimates your tax liability based on your salary and the relevant tax provisions. Factors such as your salary structure, applicable deductions or exemptions, and the tax regime you use can affect the calculation.
If tax is payable, the employer deducts TDS from your salary during the year.
A Simple Example
Suppose, after considering the applicable tax rules, your estimated annual tax liability comes to ₹60,000.
Your employer may deduct this amount from your salary throughout the year. For a simple example, this could work out to around ₹5,000 per month.
However, the actual TDS amount can be different for every employee because salary structure, deductions, exemptions and other factors may vary.
Is TDS Deducted From Every Salary?
No.
TDS does not necessarily have to be deducted from every salary.
If your taxable income and applicable tax calculation result in no tax liability, your employer may not need to deduct TDS.
This is also why two employees with similar salaries can sometimes have different TDS deductions.
Your TDS calculation can depend on more than just your monthly salary. Other relevant information and applicable tax provisions can also affect it.
So, if you see a TDS amount on your salary slip, remember that it does not automatically mean that the deducted amount is your final tax liability.
How Does TDS Apply to Bank Interest?
TDS can also apply to certain types of interest income from banks.
If you have a Fixed Deposit (FD), you earn interest on that deposit. Depending on the applicable rules and thresholds, the bank may deduct TDS from the interest.
For example, suppose you earn ₹80,000 as interest from an FD during a financial year.
If TDS is applicable, the bank may deduct the required amount and pay the remaining amount to you.
However, there is one important point to understand:
TDS deducted by the bank does not necessarily mean that your final tax liability is the same amount.
Your final tax liability depends on your total taxable income and the tax rules applicable to you.
A Simple Example of TDS on FD Interest
Suppose your FD earns ₹80,000 in interest during a financial year and the bank deducts ₹8,000 as TDS.
This does not automatically mean that your final tax liability is ₹8,000.
When you file your Income Tax Return (ITR), your overall income is considered. The eligible TDS already deducted can then be adjusted against your final tax liability.
If your actual tax liability is lower than the TDS already deducted, you may be eligible for a tax refund, subject to the applicable rules.
If your actual tax liability is higher than the TDS deducted, you may have to pay the remaining tax.
What Is the Difference Between TDS and Final Tax?
This is one of the most important things to understand.
TDS: Tax deducted in advance from certain income or payments.
Final Tax: The actual tax liability calculated after considering your total taxable income and applicable tax rules for the financial year.
These two amounts do not always have to be the same.
For example, suppose ₹50,000 of TDS has been deducted from your income during the year. After filing your ITR, your actual tax liability is calculated as ₹40,000.
In such a situation, you may be eligible for a ₹10,000 refund, subject to the applicable conditions.
On the other hand, if your final tax liability is ₹70,000 and only ₹50,000 has been deducted as TDS, you may have to pay the remaining ₹20,000.
So, TDS should not be confused with your final tax bill.
What Is Form 16?
If you are a salaried employee, Form 16 is an important tax document.
Your employer generally provides Form 16 after the end of the financial year. It contains important information about your salary income and the TDS deducted by your employer.
Form 16 can be useful when filing your ITR because it helps you verify your salary and TDS details.
Once you receive Form 16, it is a good idea to check important details such as your name, PAN, salary information and TDS amount.
What Is Form 26AS?
Form 26AS is a tax-related statement that can contain information about tax credits such as TDS.
It can help you check whether the TDS reported by your employer, bank or another deductor has been properly reflected.
Before filing your ITR, it is useful to check your available tax records so that your income and TDS information matches the reported details.
If TDS has been deducted from your salary but the amount is not properly reflected in your tax statement, you should contact your employer or the relevant deductor.
What If Too Much TDS Is Deducted?
Sometimes, more TDS may be deducted than your actual tax liability.
In such a case, you can report your correct income and eligible TDS while filing your ITR.
If the final calculation shows that you have paid more tax than required, you may be eligible for an income tax refund, subject to the applicable rules.
So, if more TDS has been deducted, it does not necessarily mean that you have permanently lost that money.
What If TDS Is Deducted but Does Not Appear in Form 26AS?
Suppose your employer or bank has deducted TDS, but you cannot see the amount properly reflected in your tax statement.
There could be several reasons for this, such as:
- The TDS statement has not been updated yet
- Incorrect PAN details
- An error in TDS reporting
- A correction is required from the deductor
In such cases, it is better to contact the employer, bank or relevant deductor and get the details checked before filing your ITR.
Why Is PAN Important for TDS?
PAN plays an important role in TDS reporting.
Your PAN details should be correctly updated with your employer, bank and other relevant institutions.
If your PAN information is incorrect or unavailable where required, TDS may be deducted at a higher rate in certain situations, as per the applicable rules.
Therefore, keeping your PAN details correct in your financial records is important.
Do You Need to File an ITR After TDS Is Deducted?
Simply having TDS deducted does not automatically determine whether you are required to file an ITR.
Your ITR filing requirement depends on your total income and the applicable income-tax rules.
For example, you may have income from salary as well as bank interest, FD interest, rent or other sources.
Therefore, you should consider your overall income instead of assuming that no further action is needed just because TDS has already been deducted.
In simple words, TDS being deducted does not mean you can automatically ignore your ITR.
How Can You Understand TDS Easily?
If you want to understand TDS in one simple sentence, think of it this way:
“TDS means deducting the applicable tax from certain income or payments before the money is paid to you.”
Your employer may deduct TDS from your salary.
A bank may deduct TDS from certain interest income, such as FD interest, when the applicable conditions are met.
The TDS already deducted can then be considered while calculating your final tax liability.
If more tax has been deducted than required, you may be eligible for a refund. If less tax has been deducted, you may have to pay the remaining amount.
Conclusion
TDS may sound complicated at first, but the basic concept is actually quite simple.
TDS stands for Tax Deducted at Source. It means that tax is deducted at the source of certain payments before the income reaches you.
For salaried employees, the employer may deduct TDS from salary. Similarly, banks may deduct TDS from certain interest payments, including FD interest, when the applicable rules and thresholds are met.
The most important thing to remember is that TDS and your final tax liability are not necessarily the same thing.
TDS is tax that has already been deducted, while your final tax liability is calculated based on your total taxable income and the applicable tax rules for the financial year.
That is why it is useful to keep track of your salary slips, Form 16, bank interest details and tax statements. When filing your ITR, make sure your income and TDS details are reported correctly.
If more TDS has been deducted than your final tax liability, you may be eligible for a refund. If the TDS deducted is less than your final tax liability, you may need to pay additional tax.
Since tax rules, thresholds and TDS rates can change from time to time, always check the current income-tax rules for the relevant financial year or transaction.